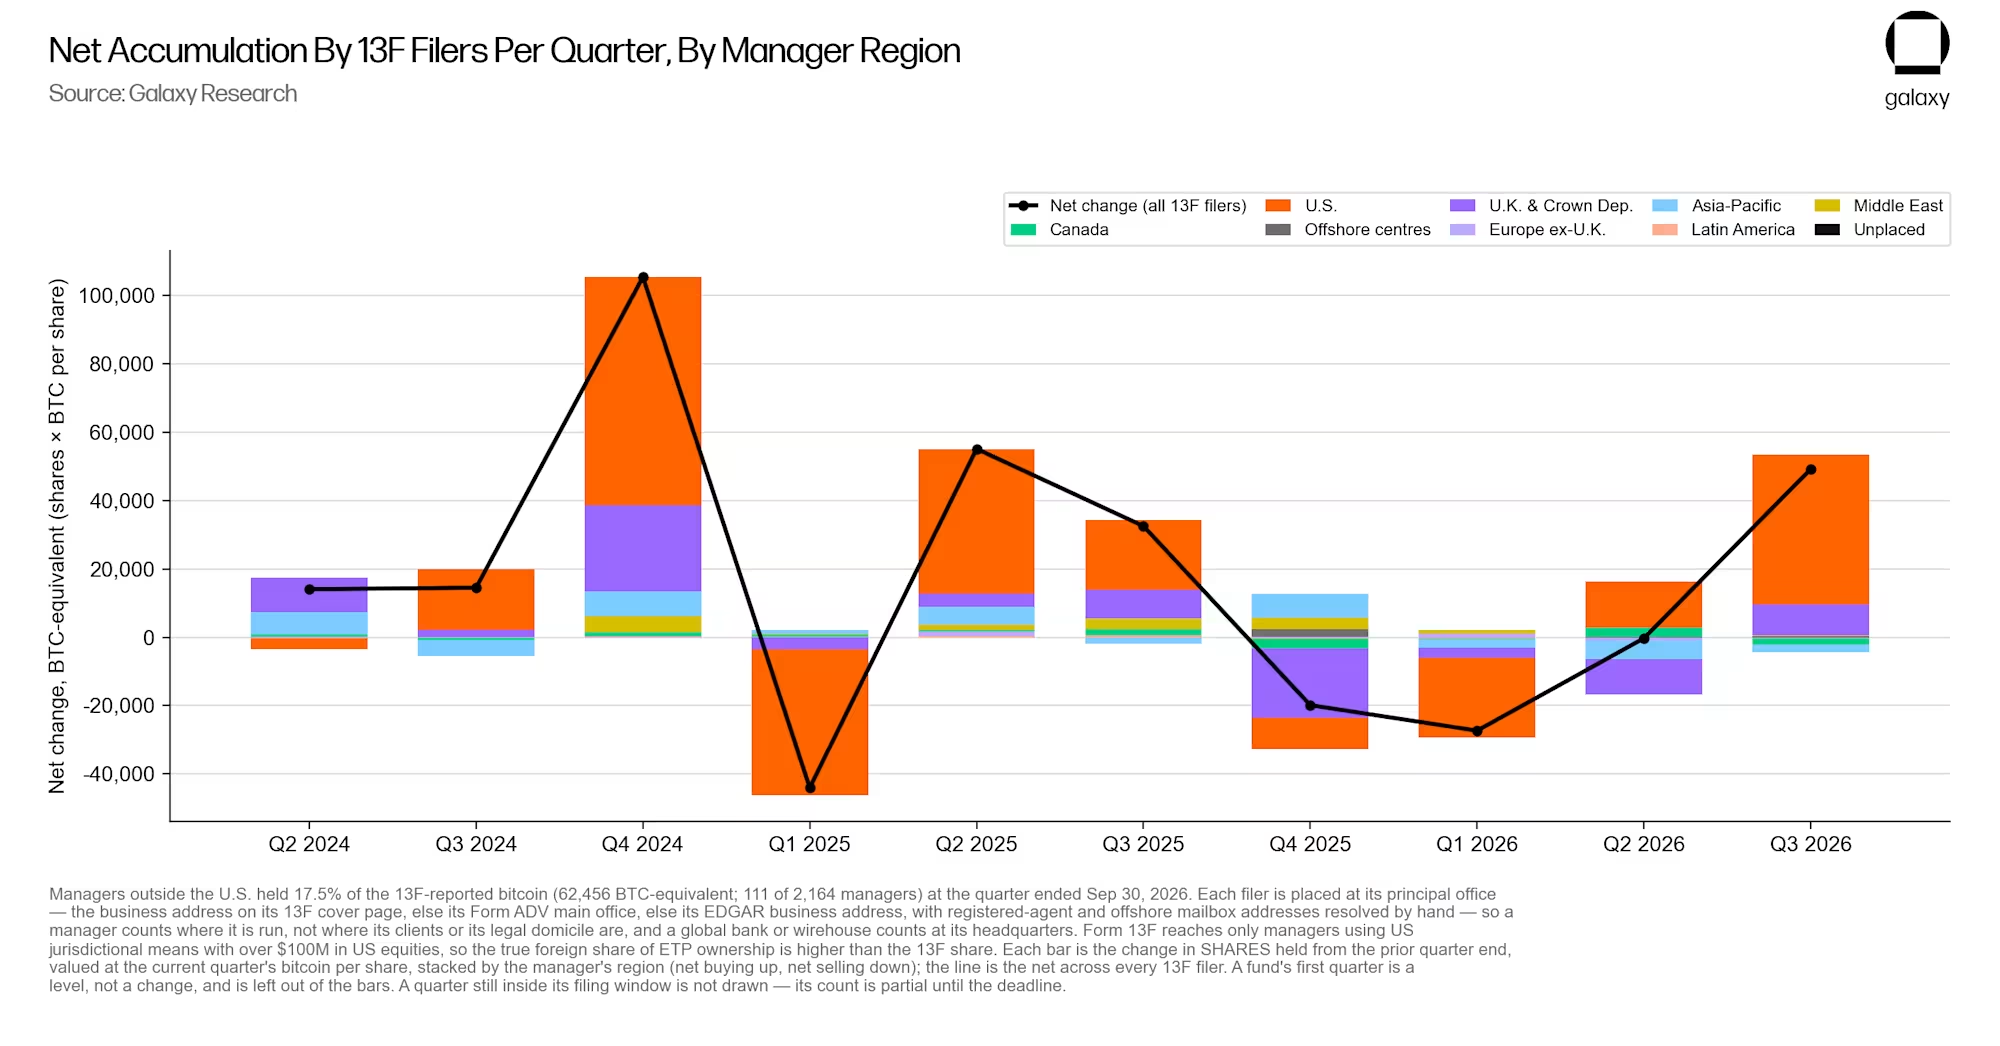
As reported on November 20, 2026, an analysis of Form 13F filings found that investment managers increased their reported holdings of US spot Bitcoin exchange-traded products (ETPs) in the third quarter. The net increase was equivalent to 49,229 BTC, more than the 47,054 BTC these managers had collectively reduced their holdings by over the preceding three quarters.
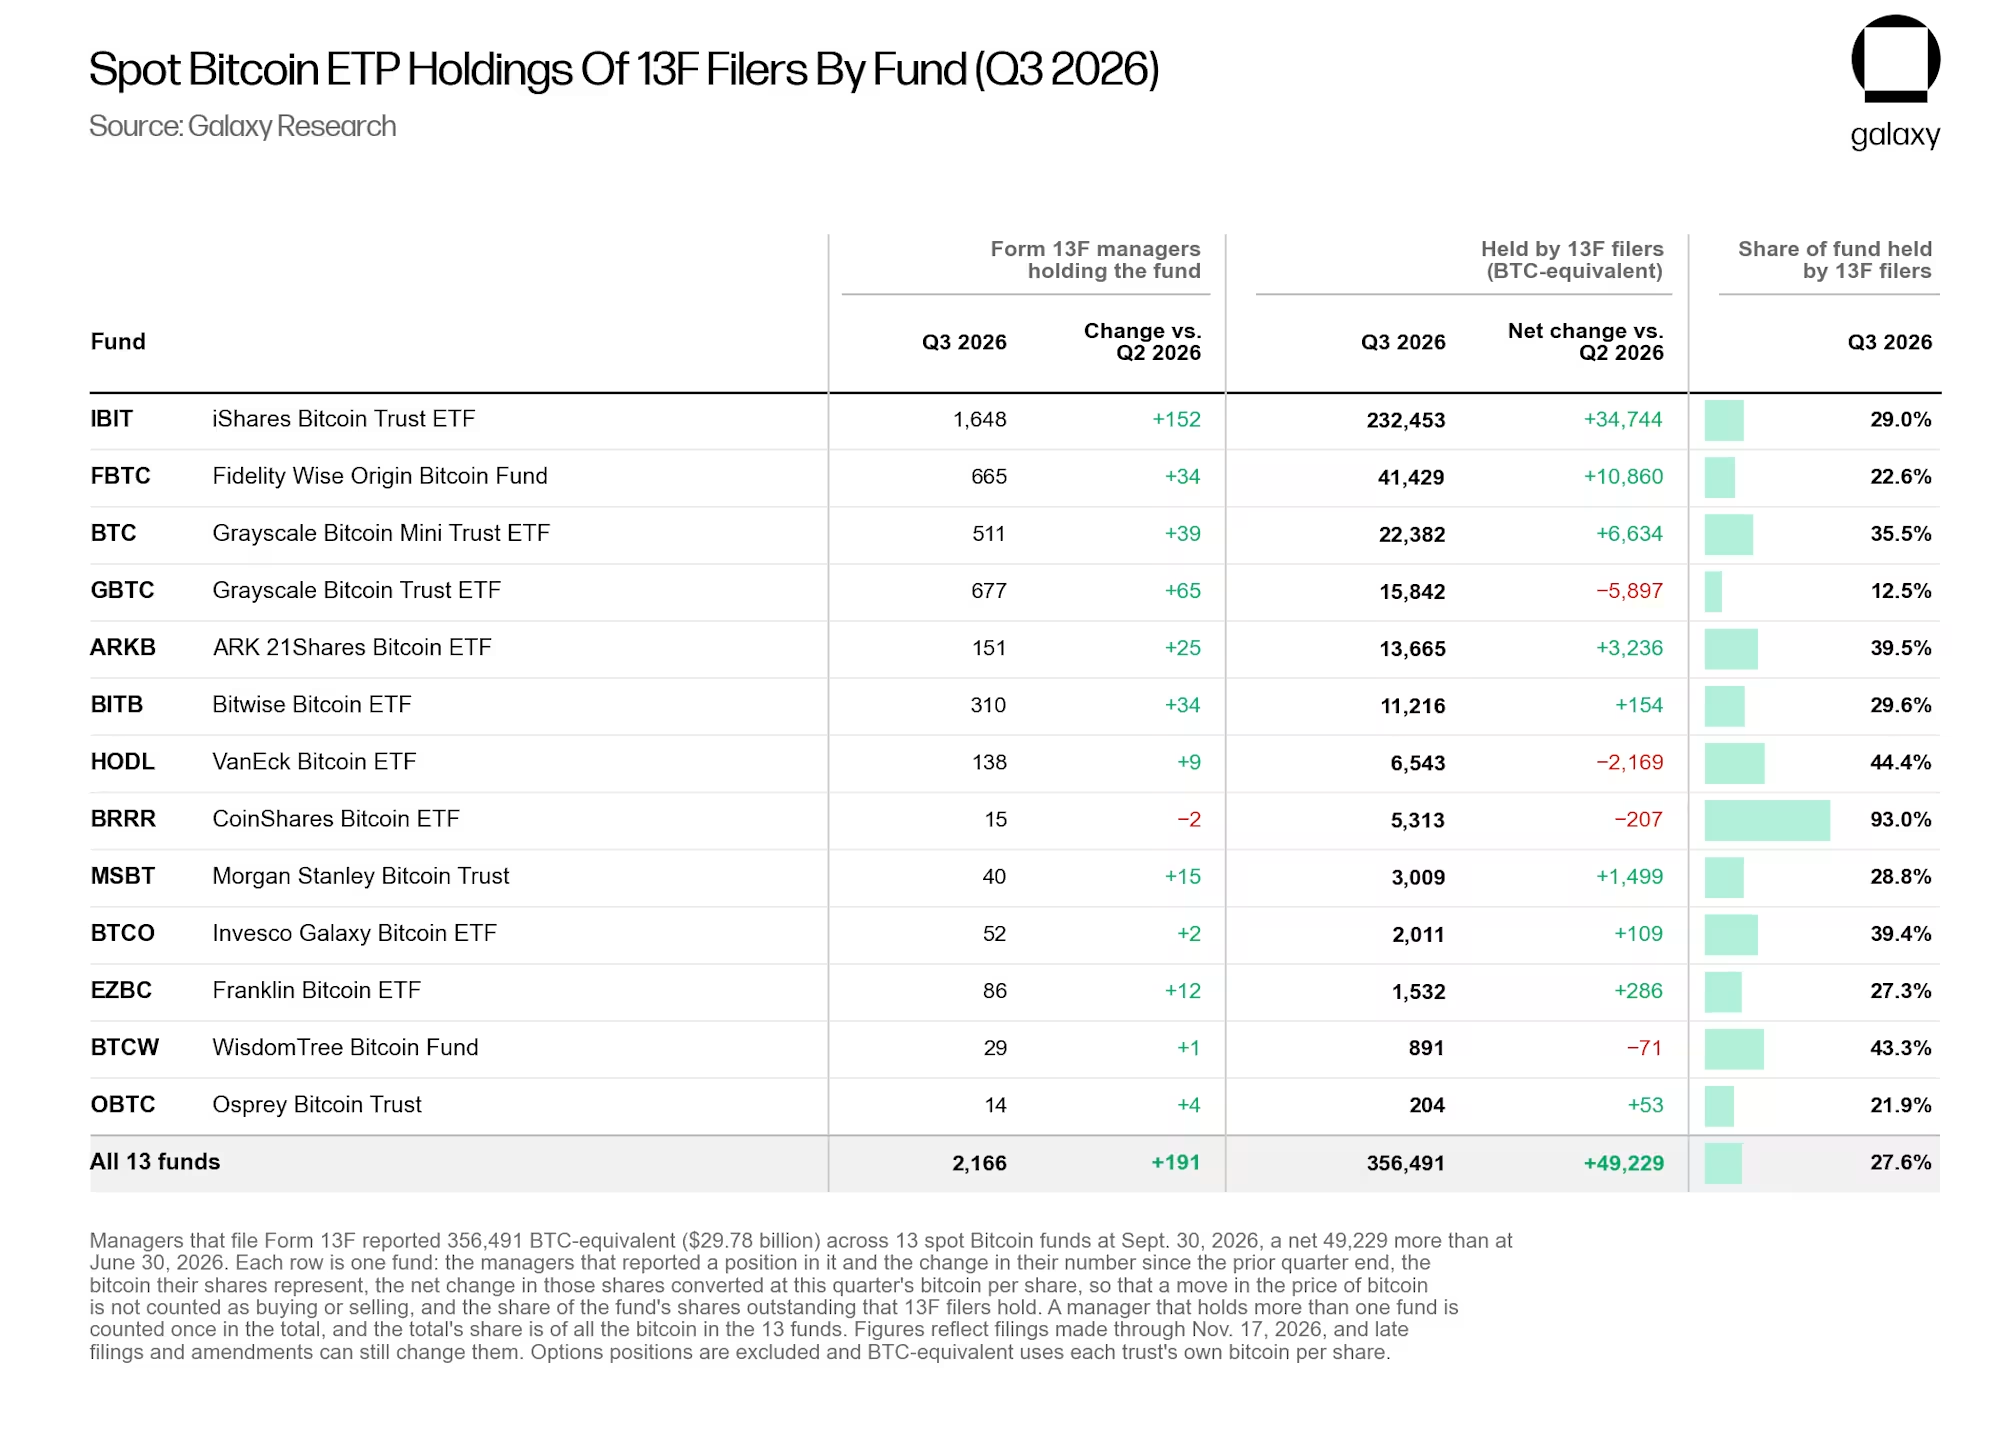
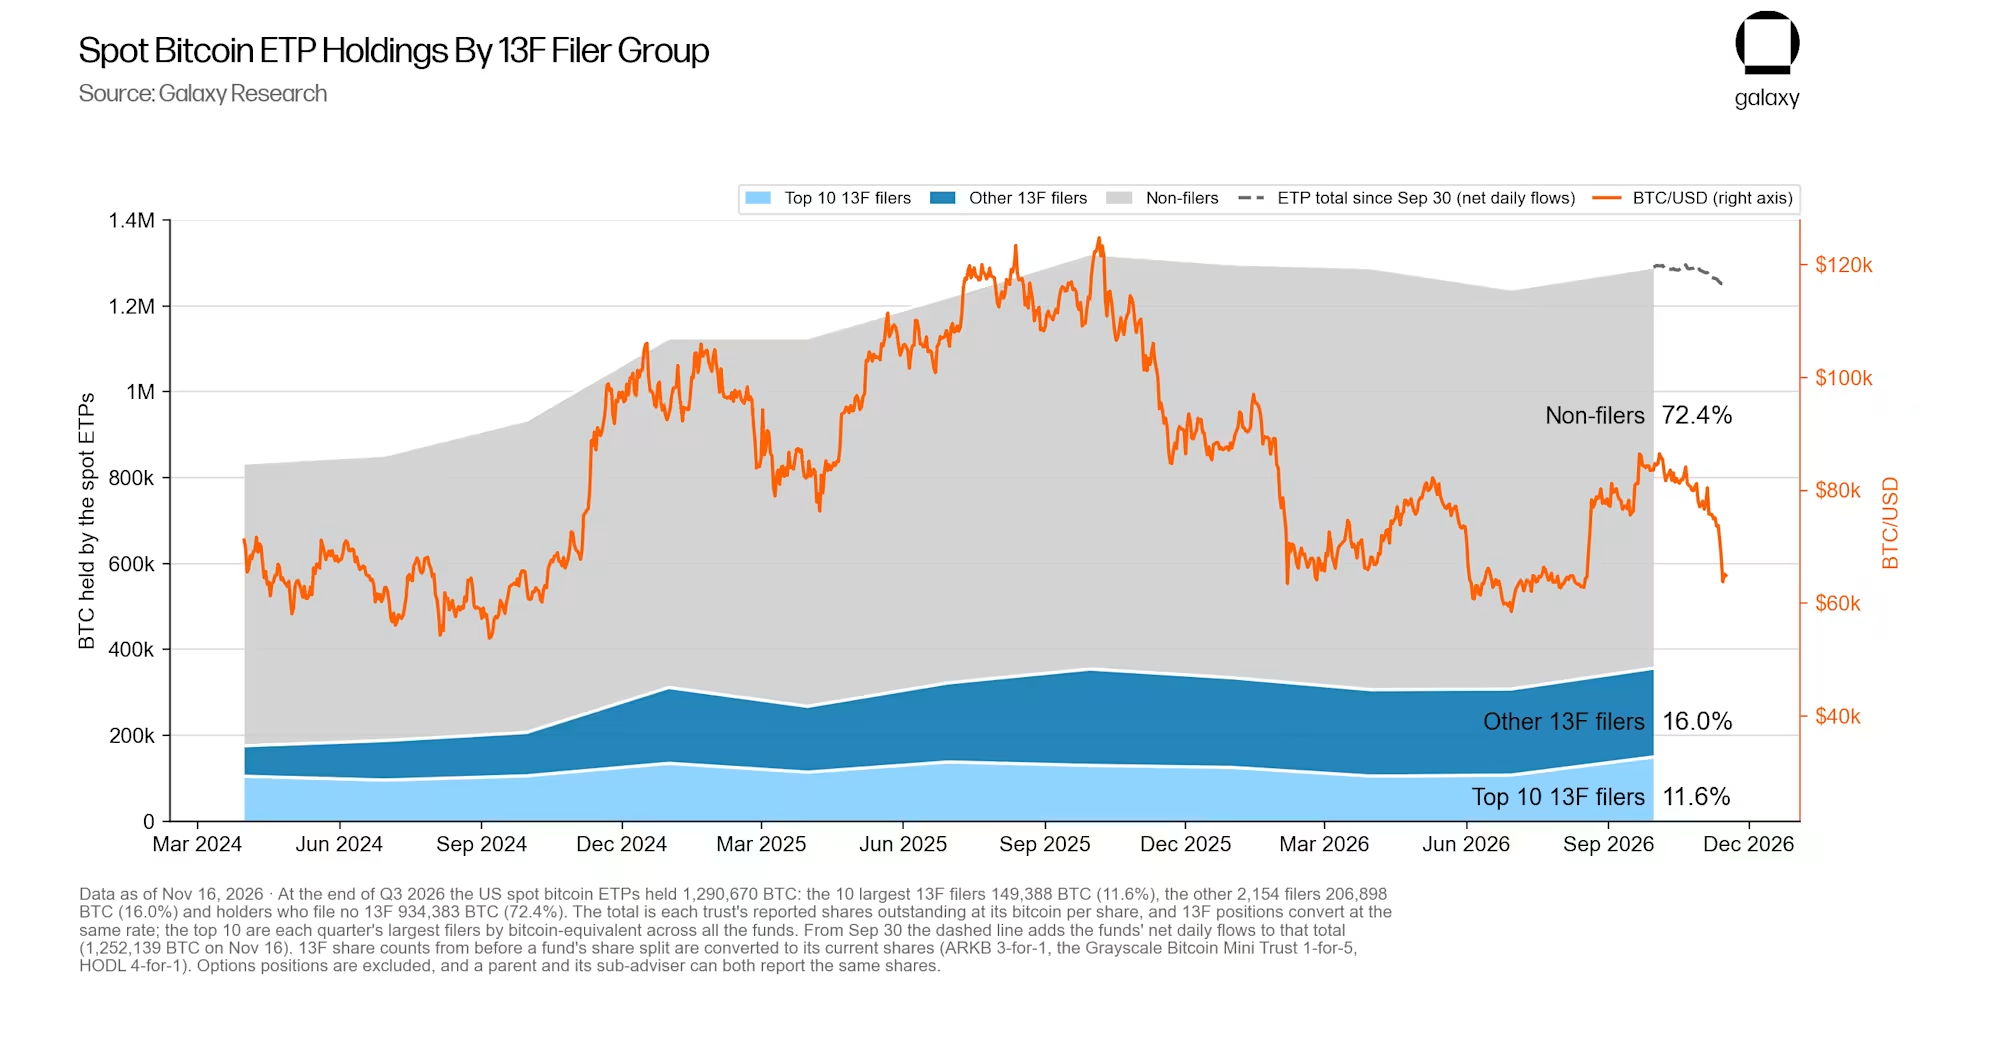
The central question is whether that increase reflects broad, lasting demand. The filings show more managers holding the products, but most of the increase in reported Bitcoin exposure came from a small group of large holders.
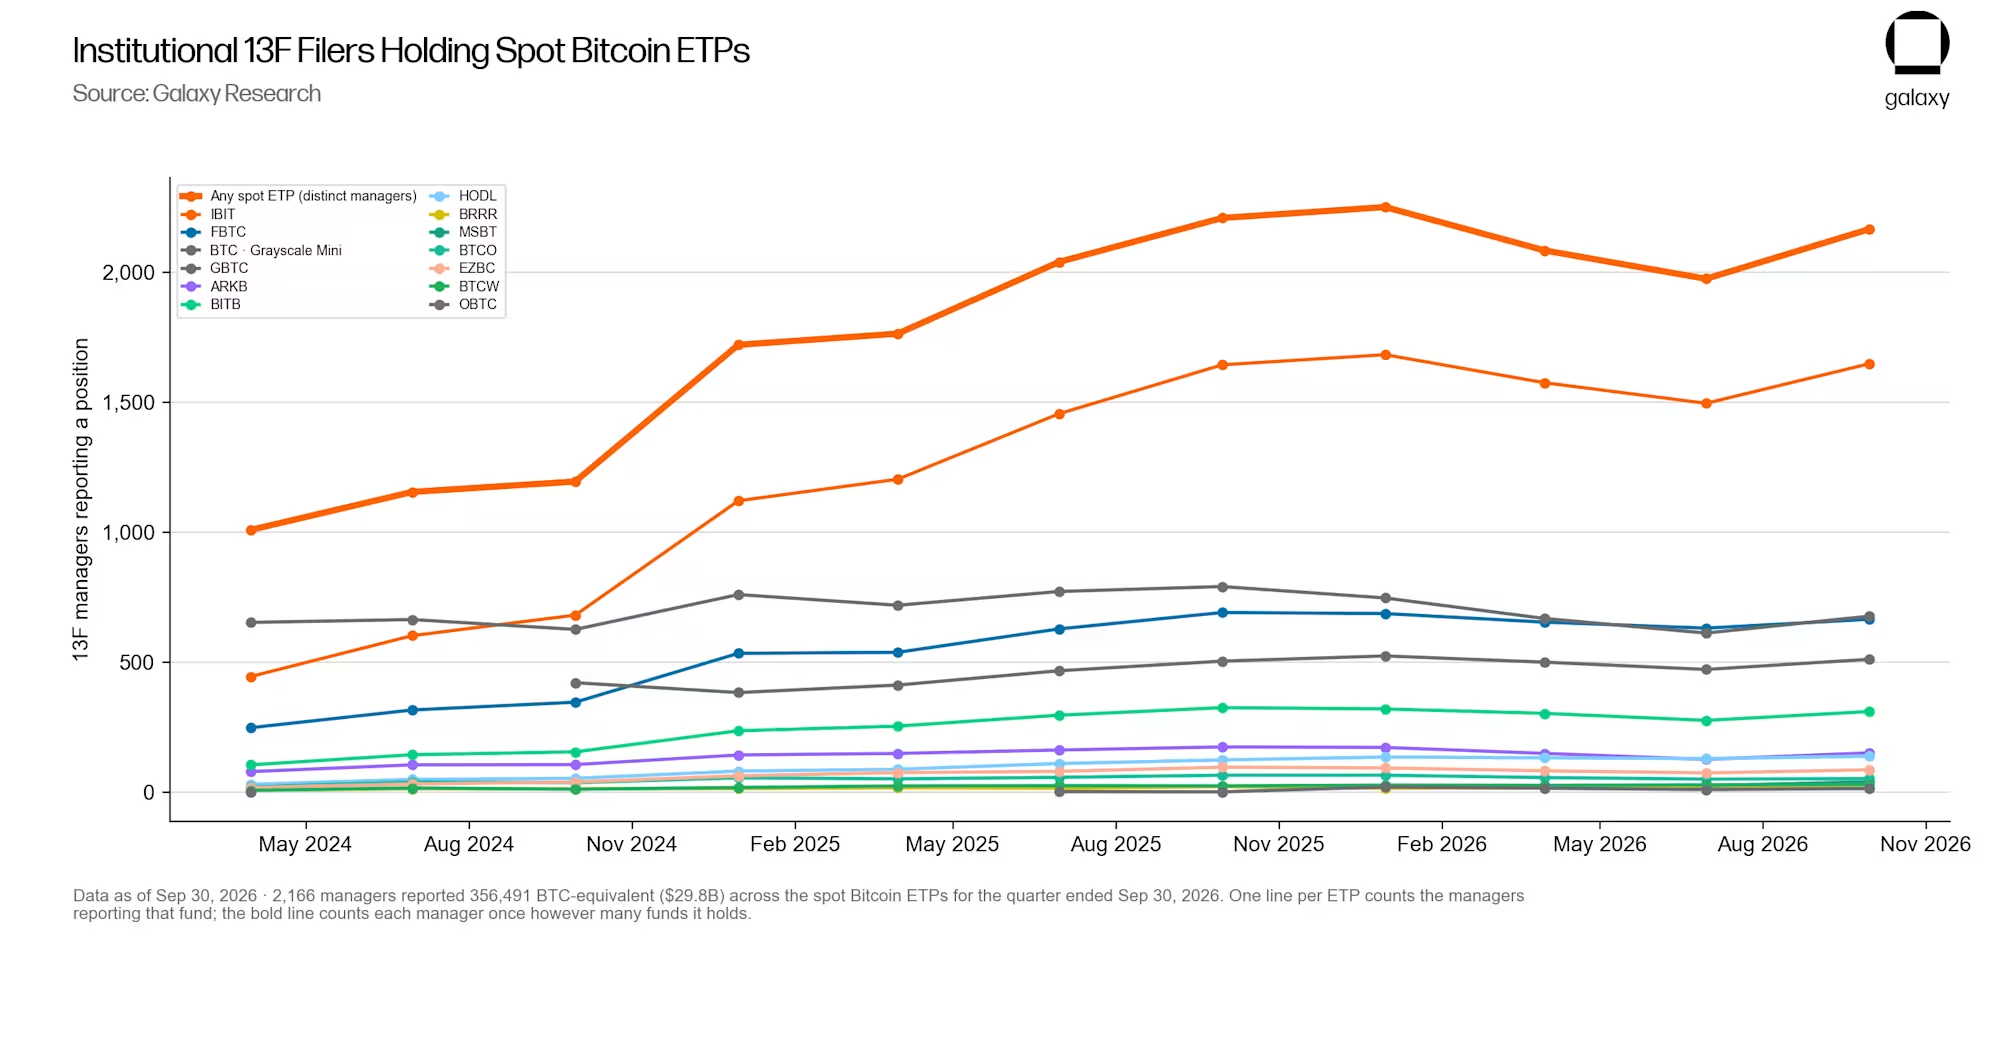
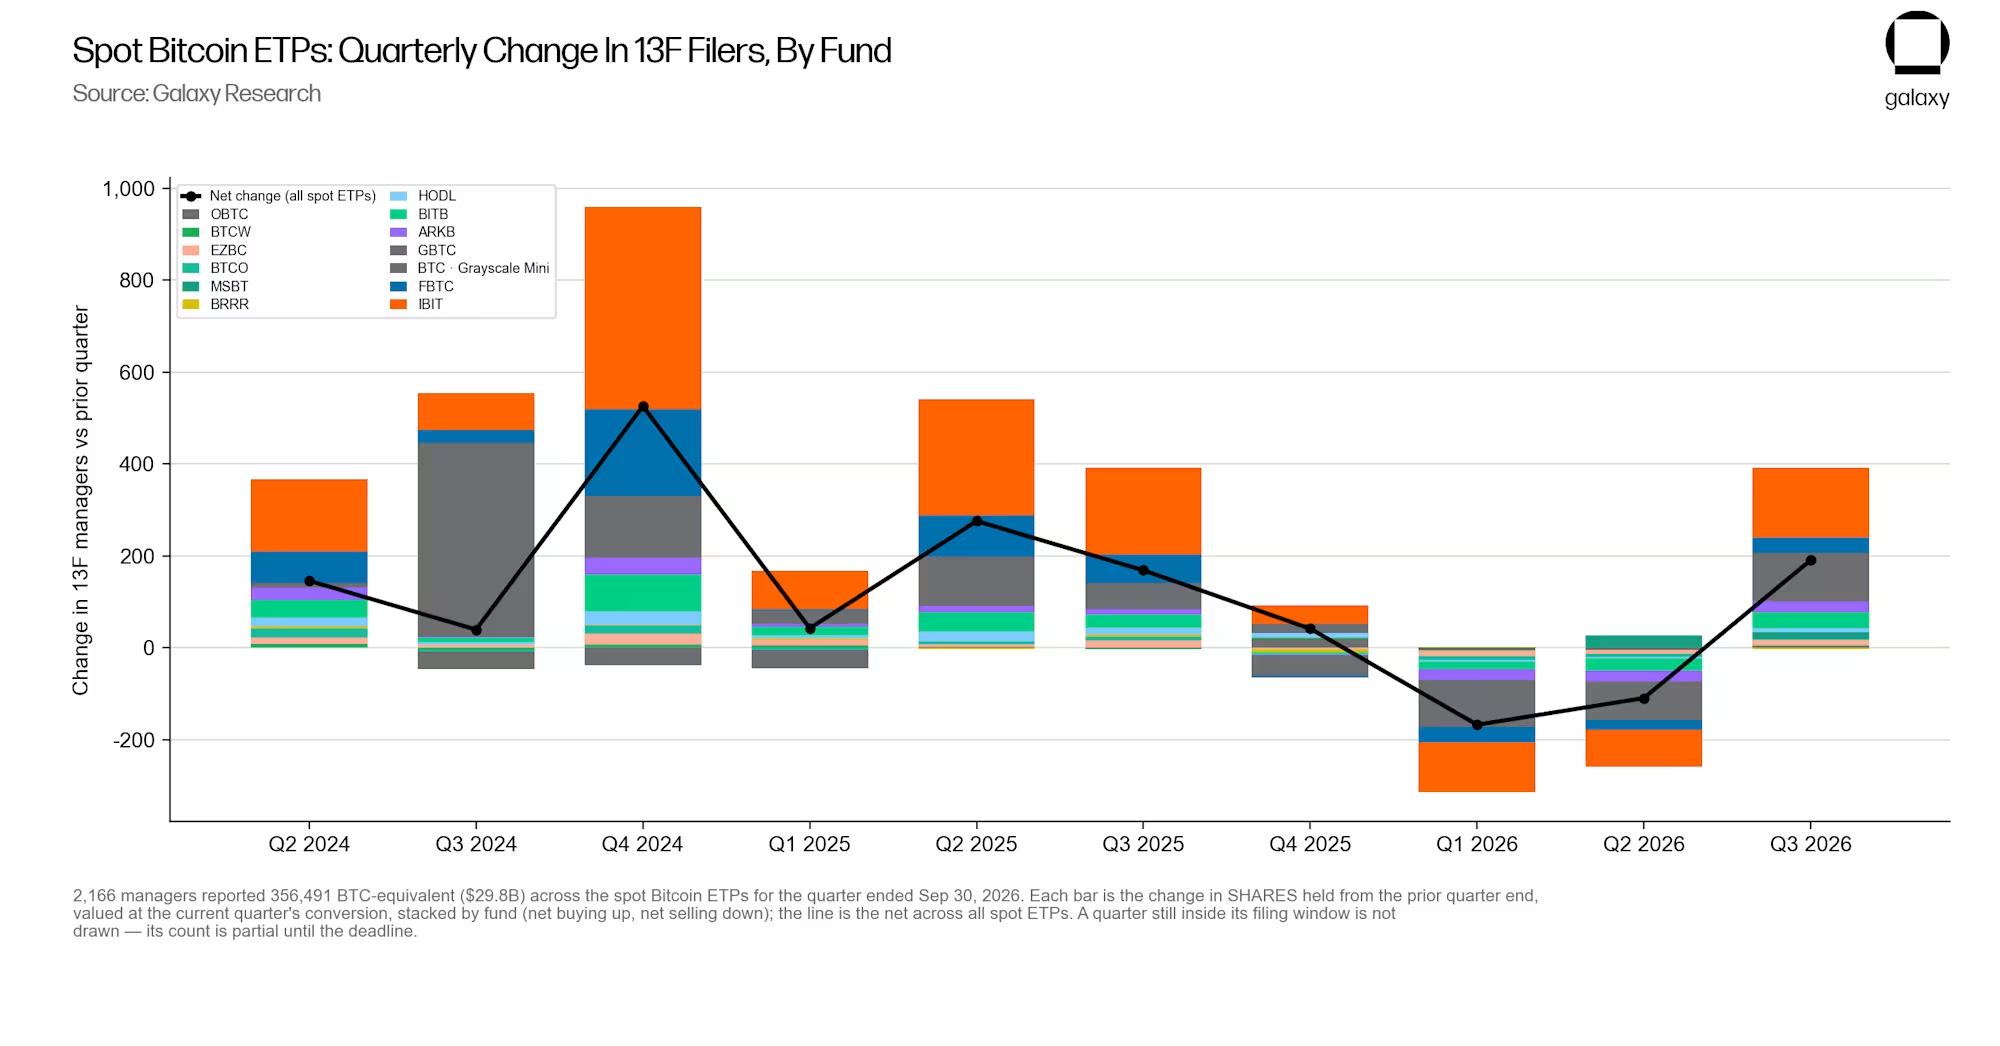
More holders, concentrated growth
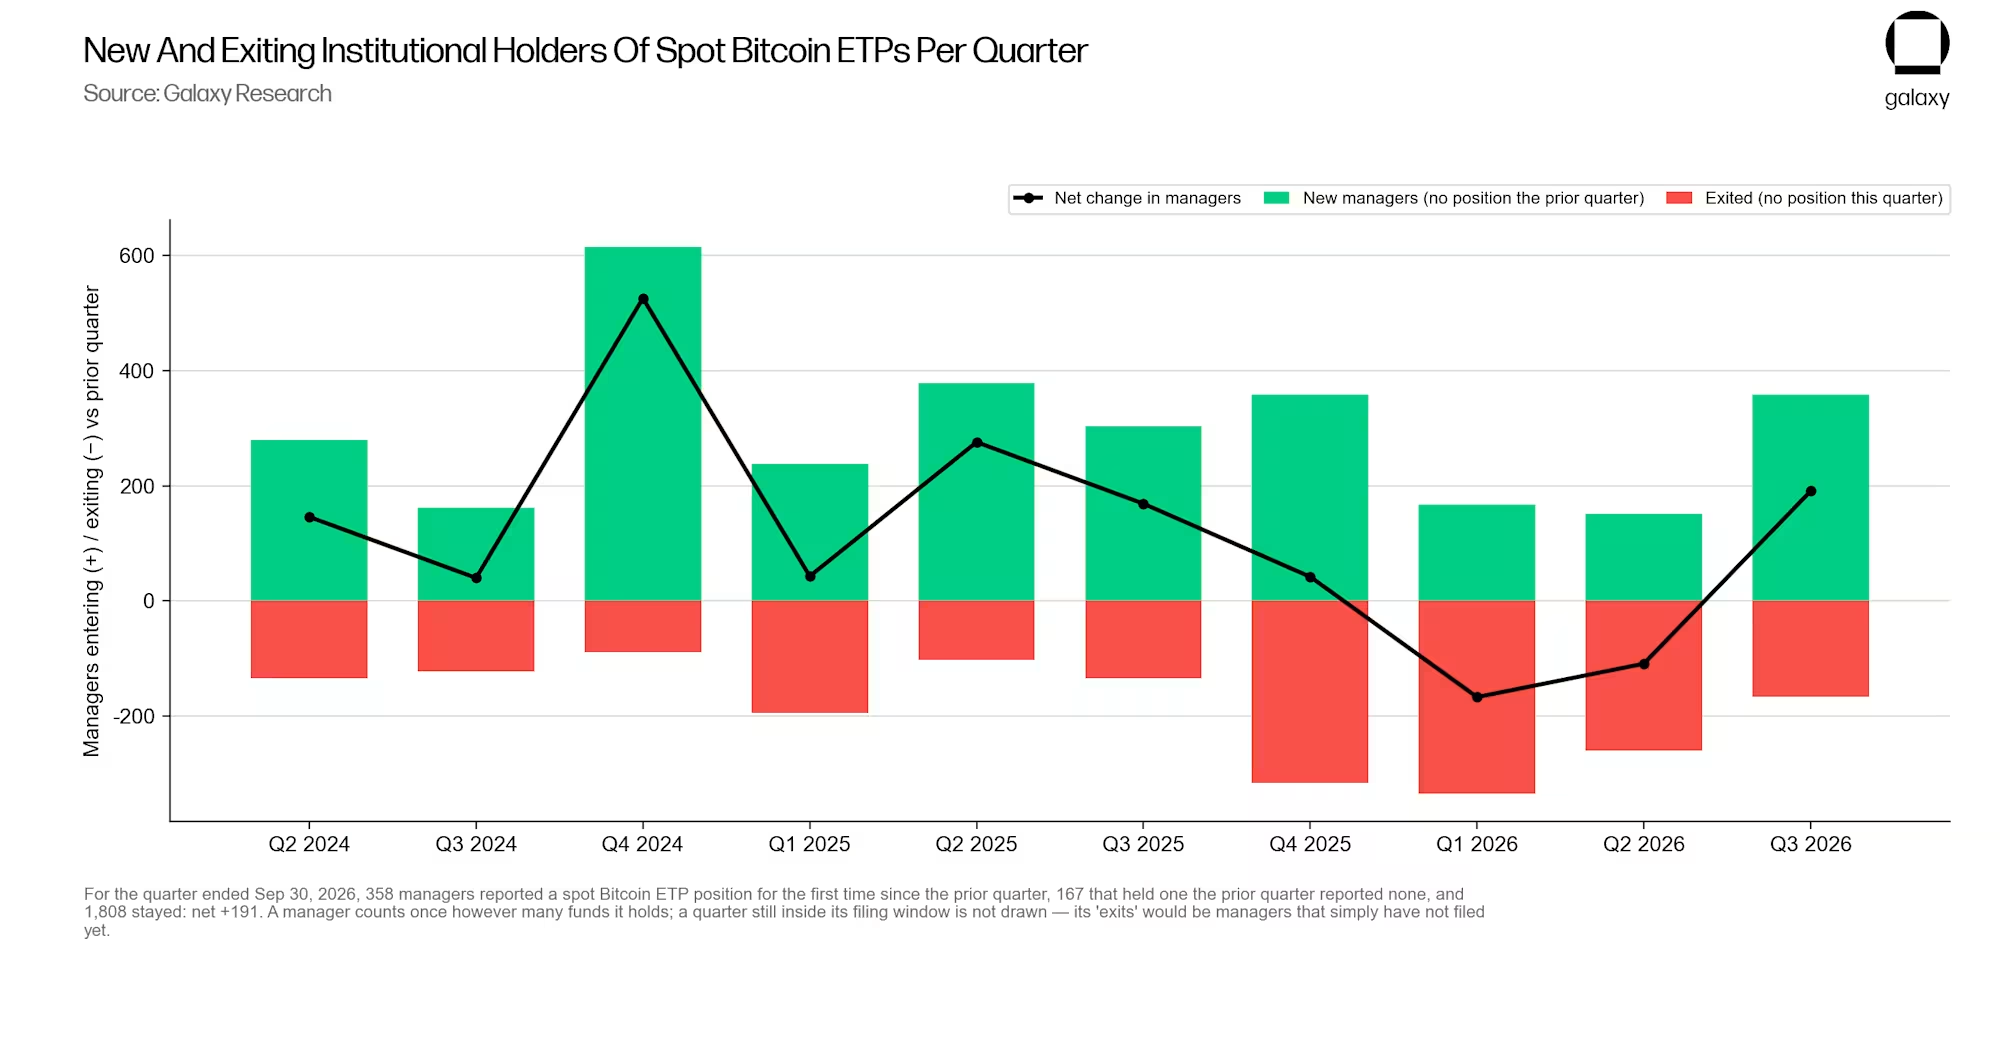
The number of managers reporting at least one spot Bitcoin ETP holding rose by 191 to 2,166 as of September 30, 2026. Of those, 358 had not reported a holding in the previous quarter, while 167 previous holders no longer reported one.
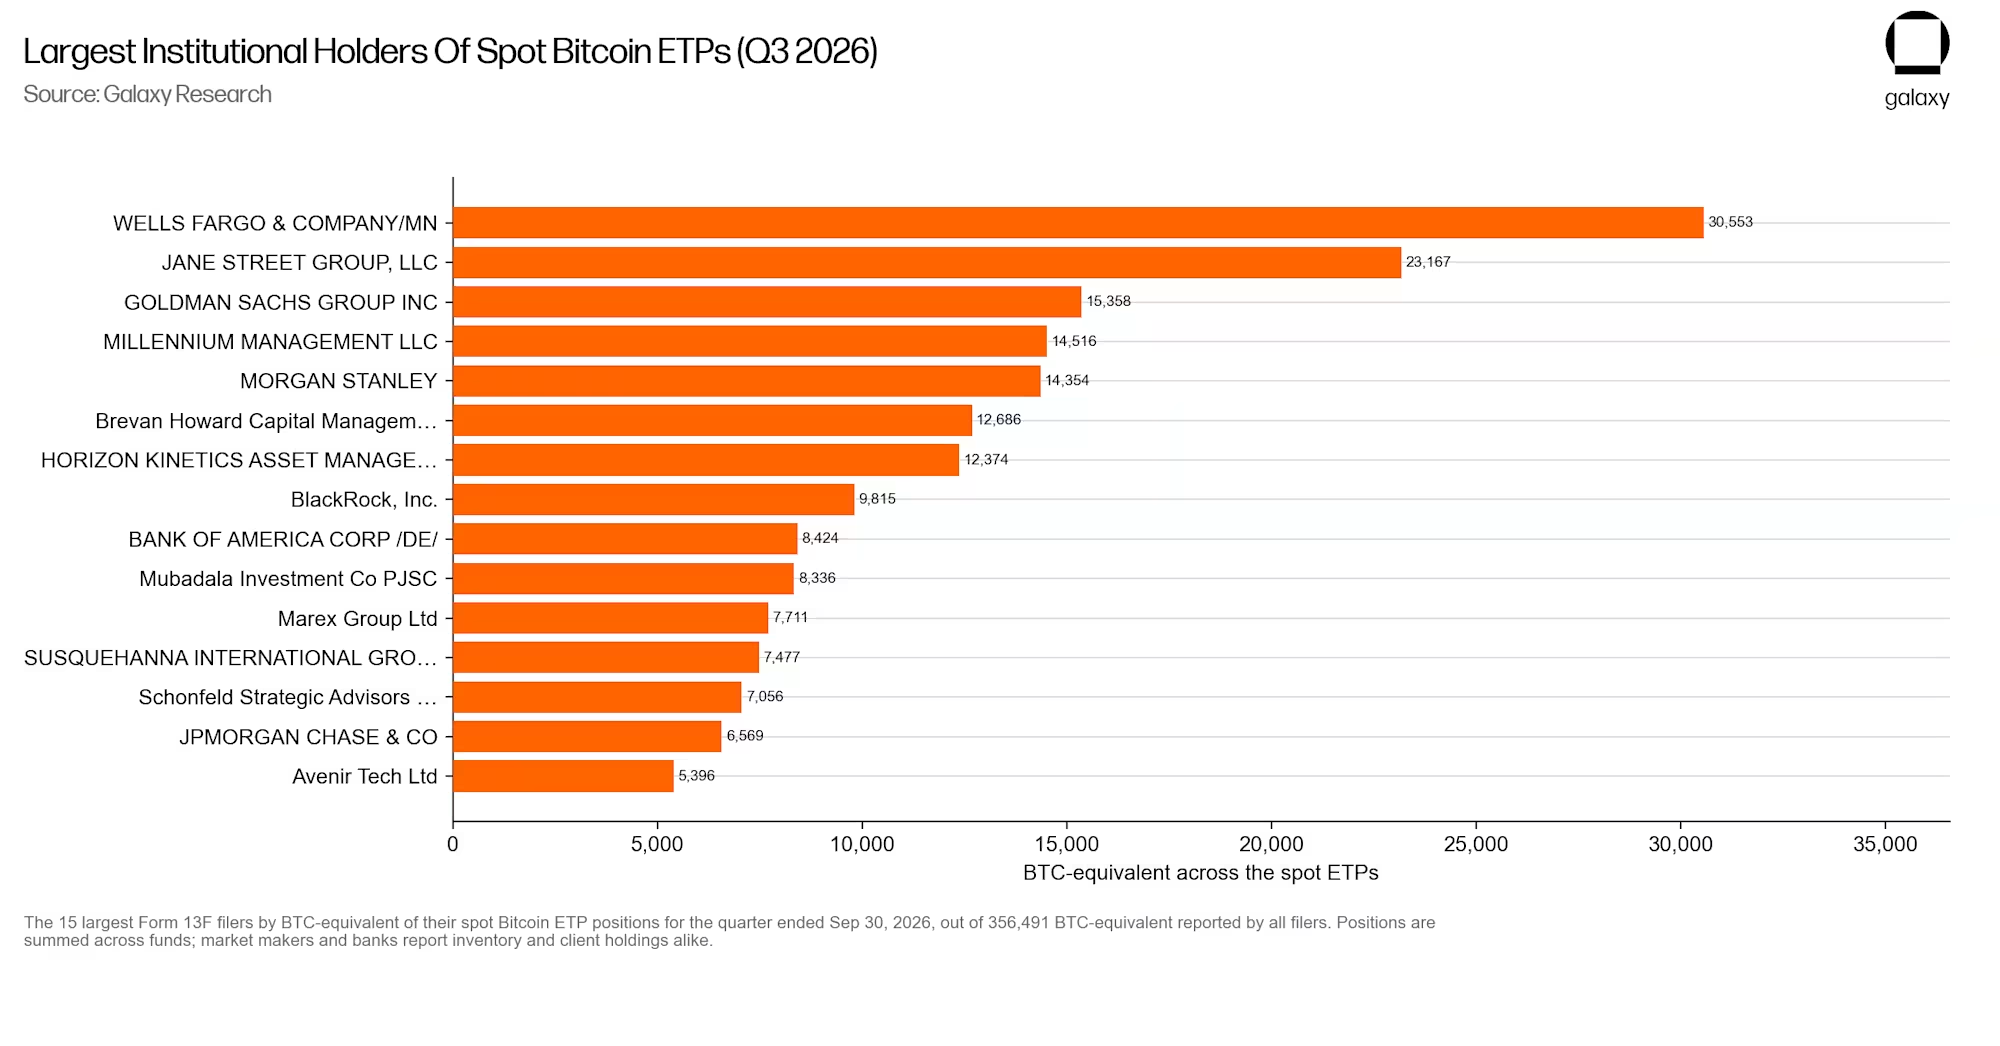
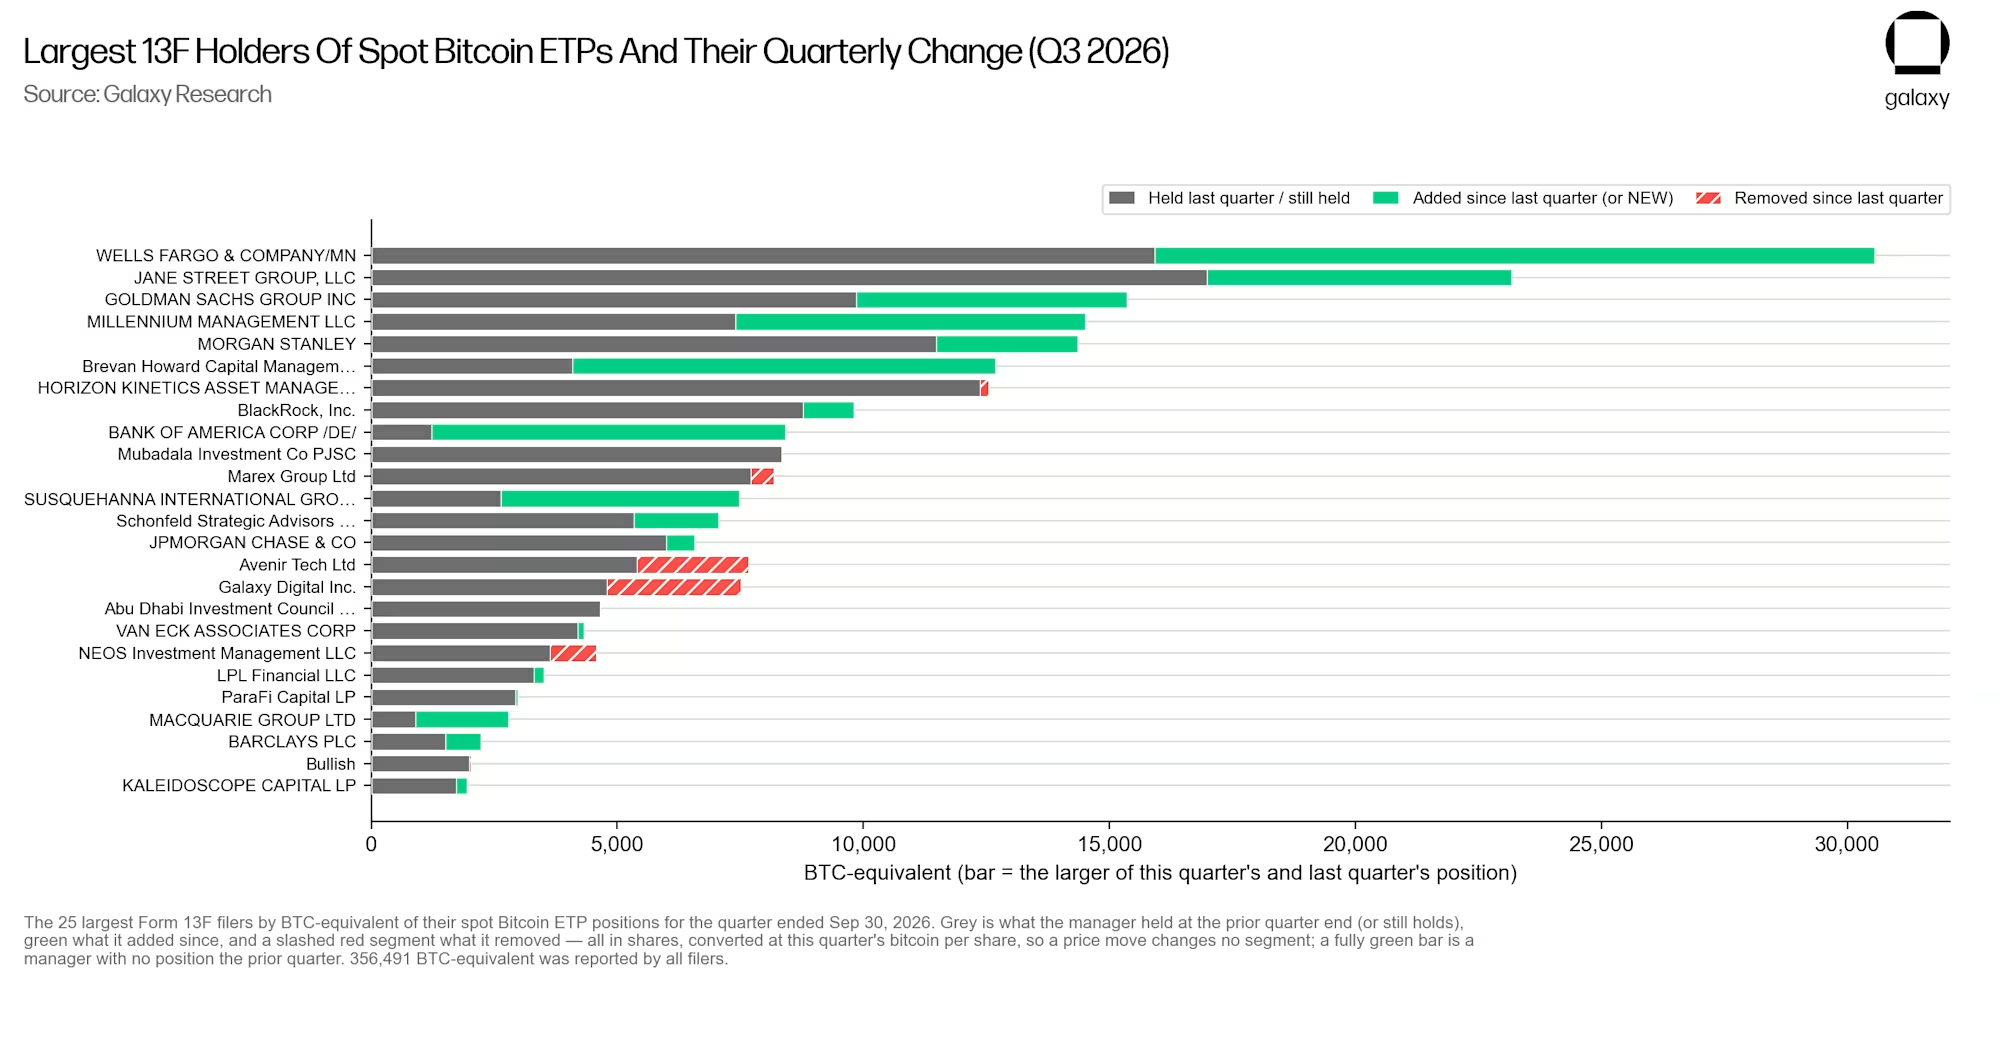
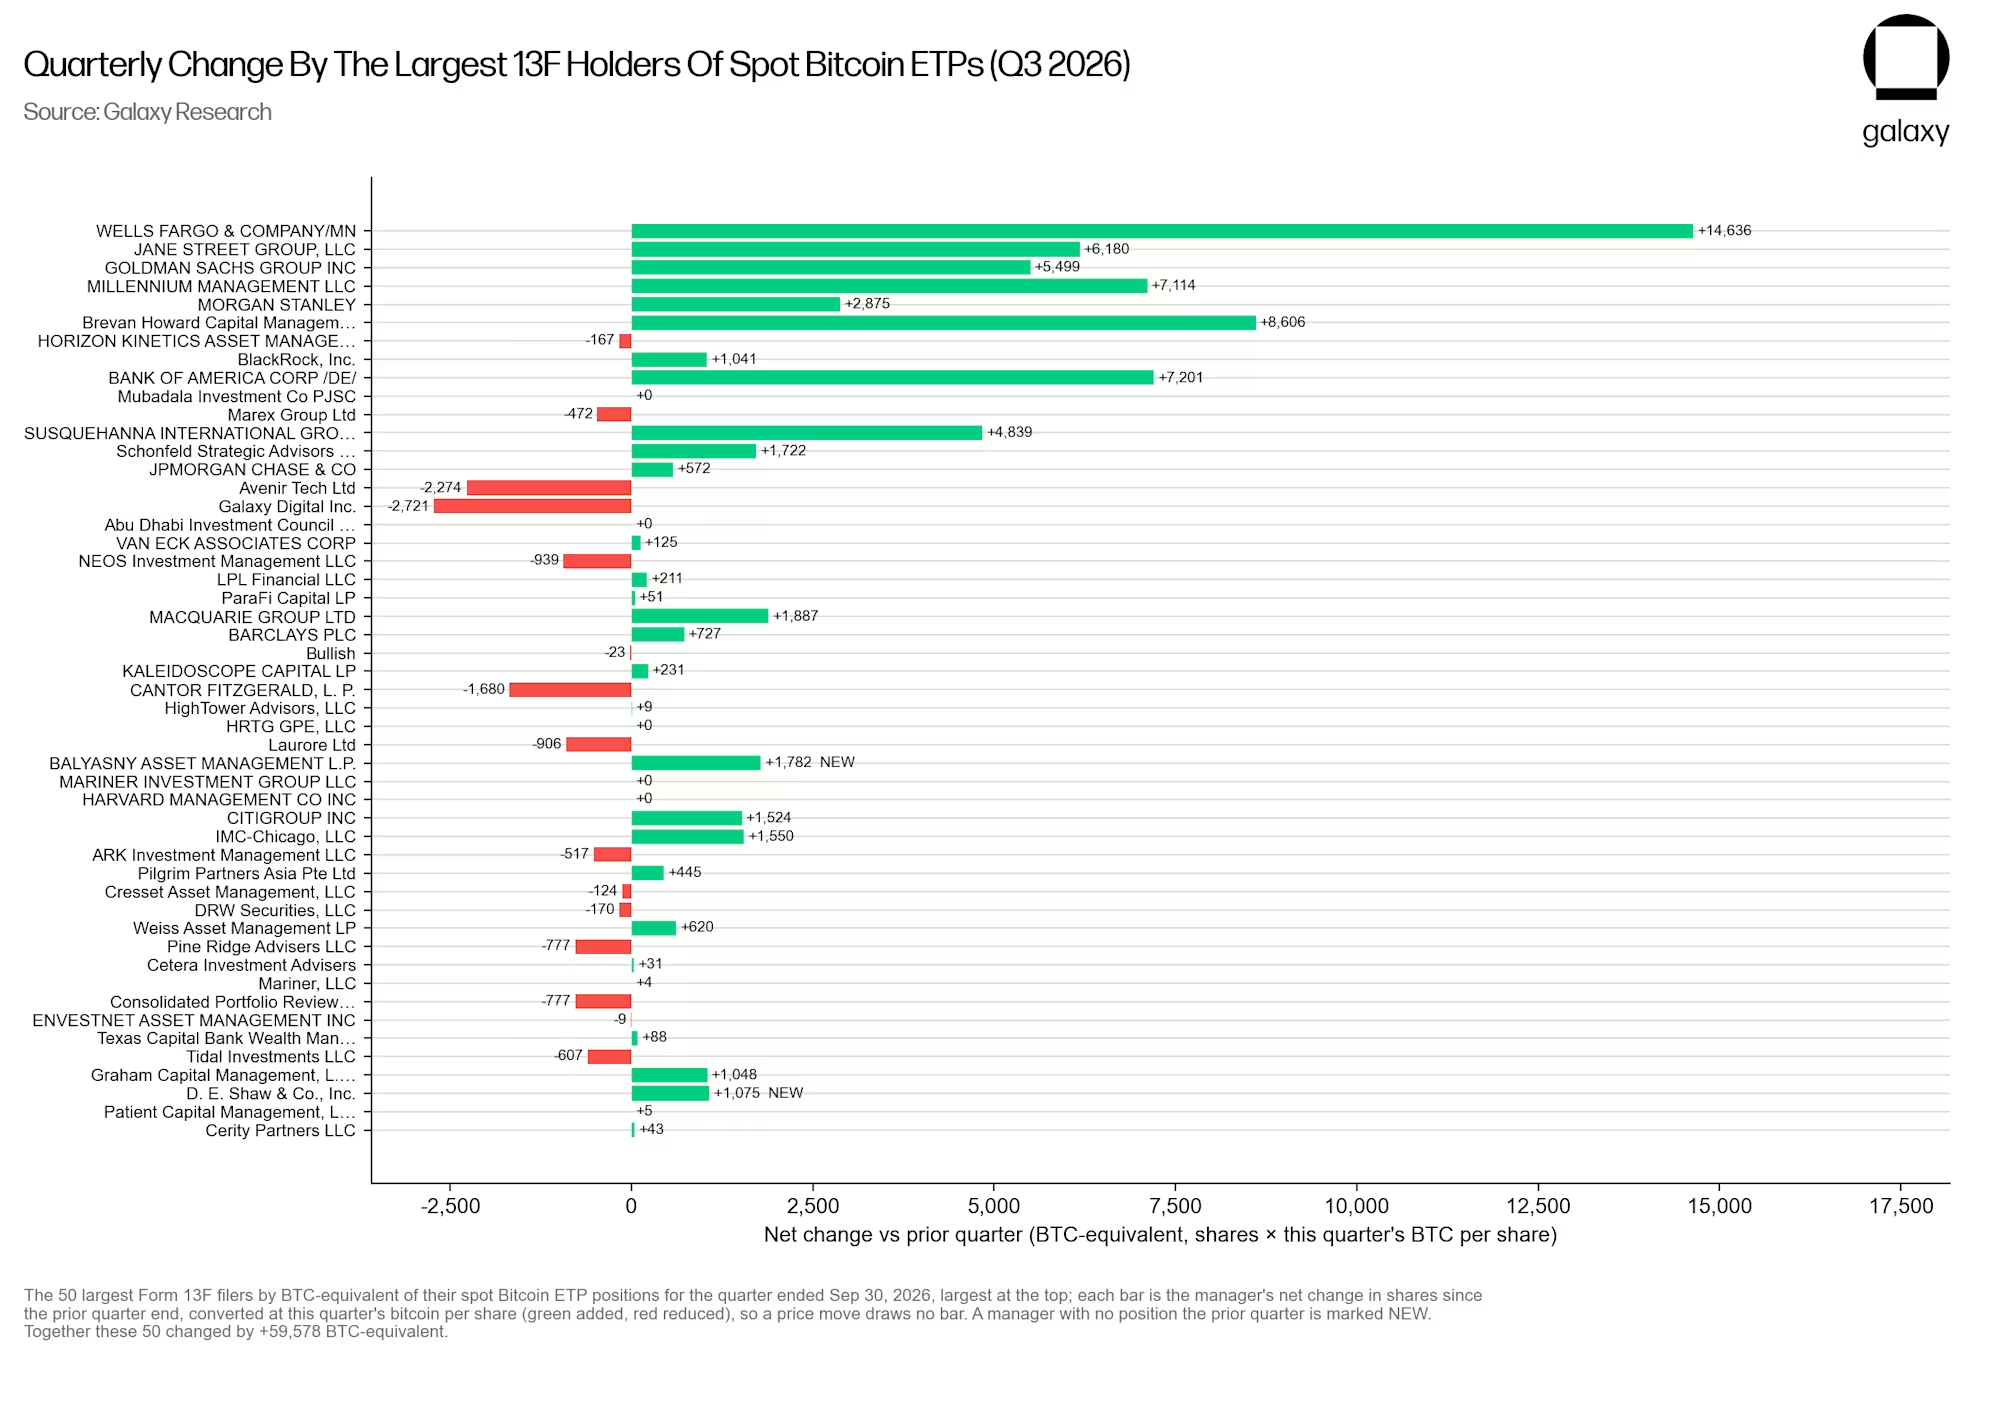
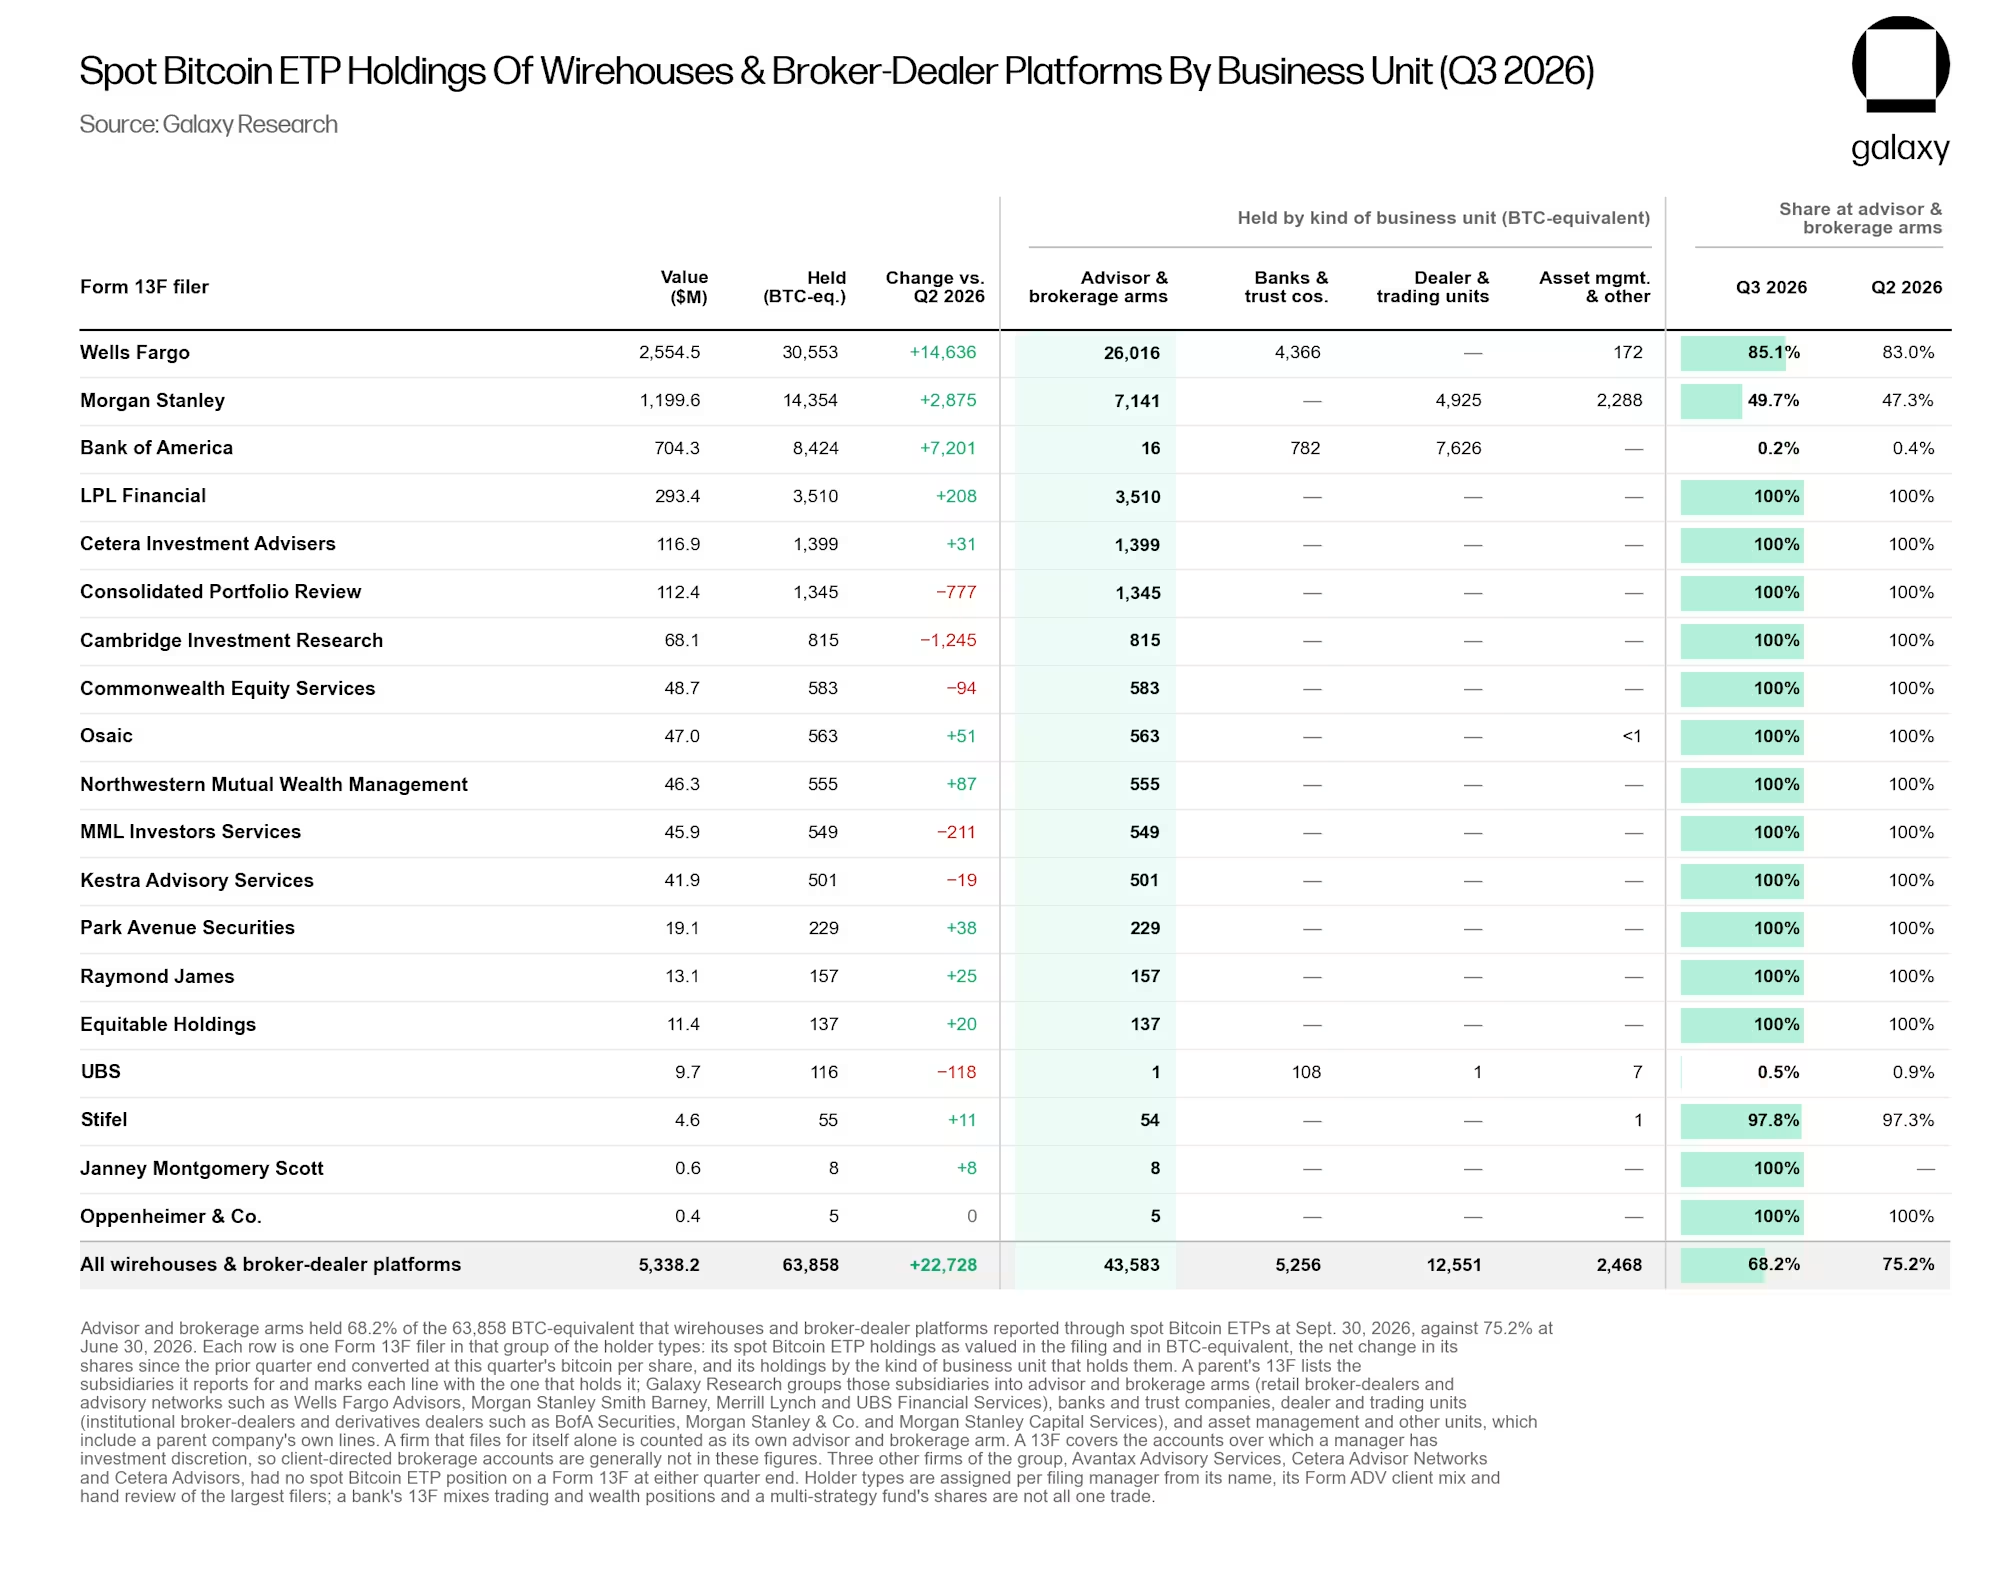
The 50 largest holders added a net 59,578 BTC equivalent. All other managers combined—including those that exited—reduced their holdings by 10,349 BTC equivalent. Wells Fargo reported the largest position, equivalent to 30,553 BTC, overtaking Jane Street.
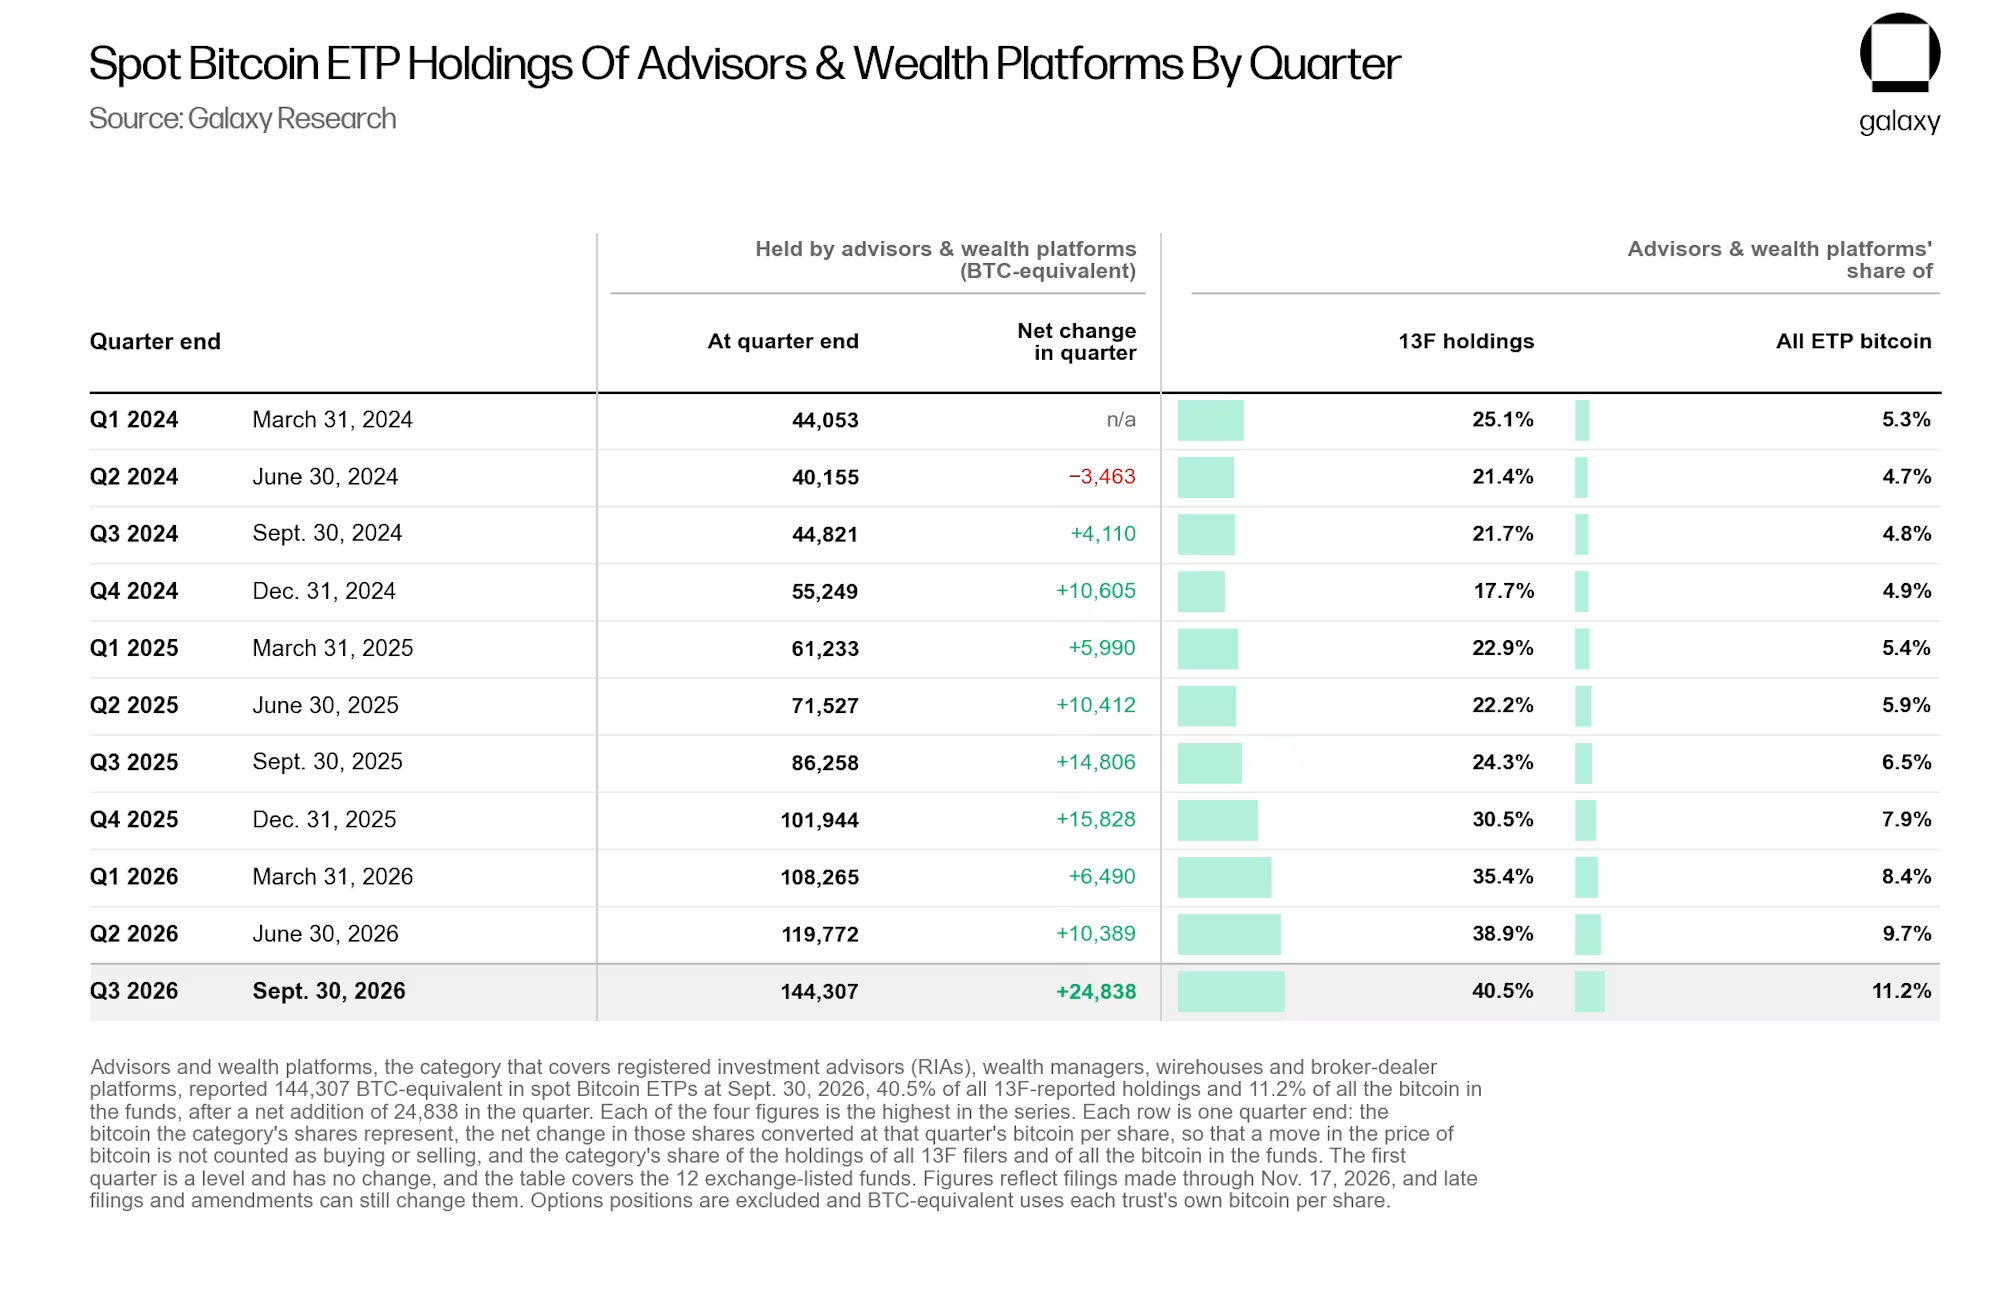
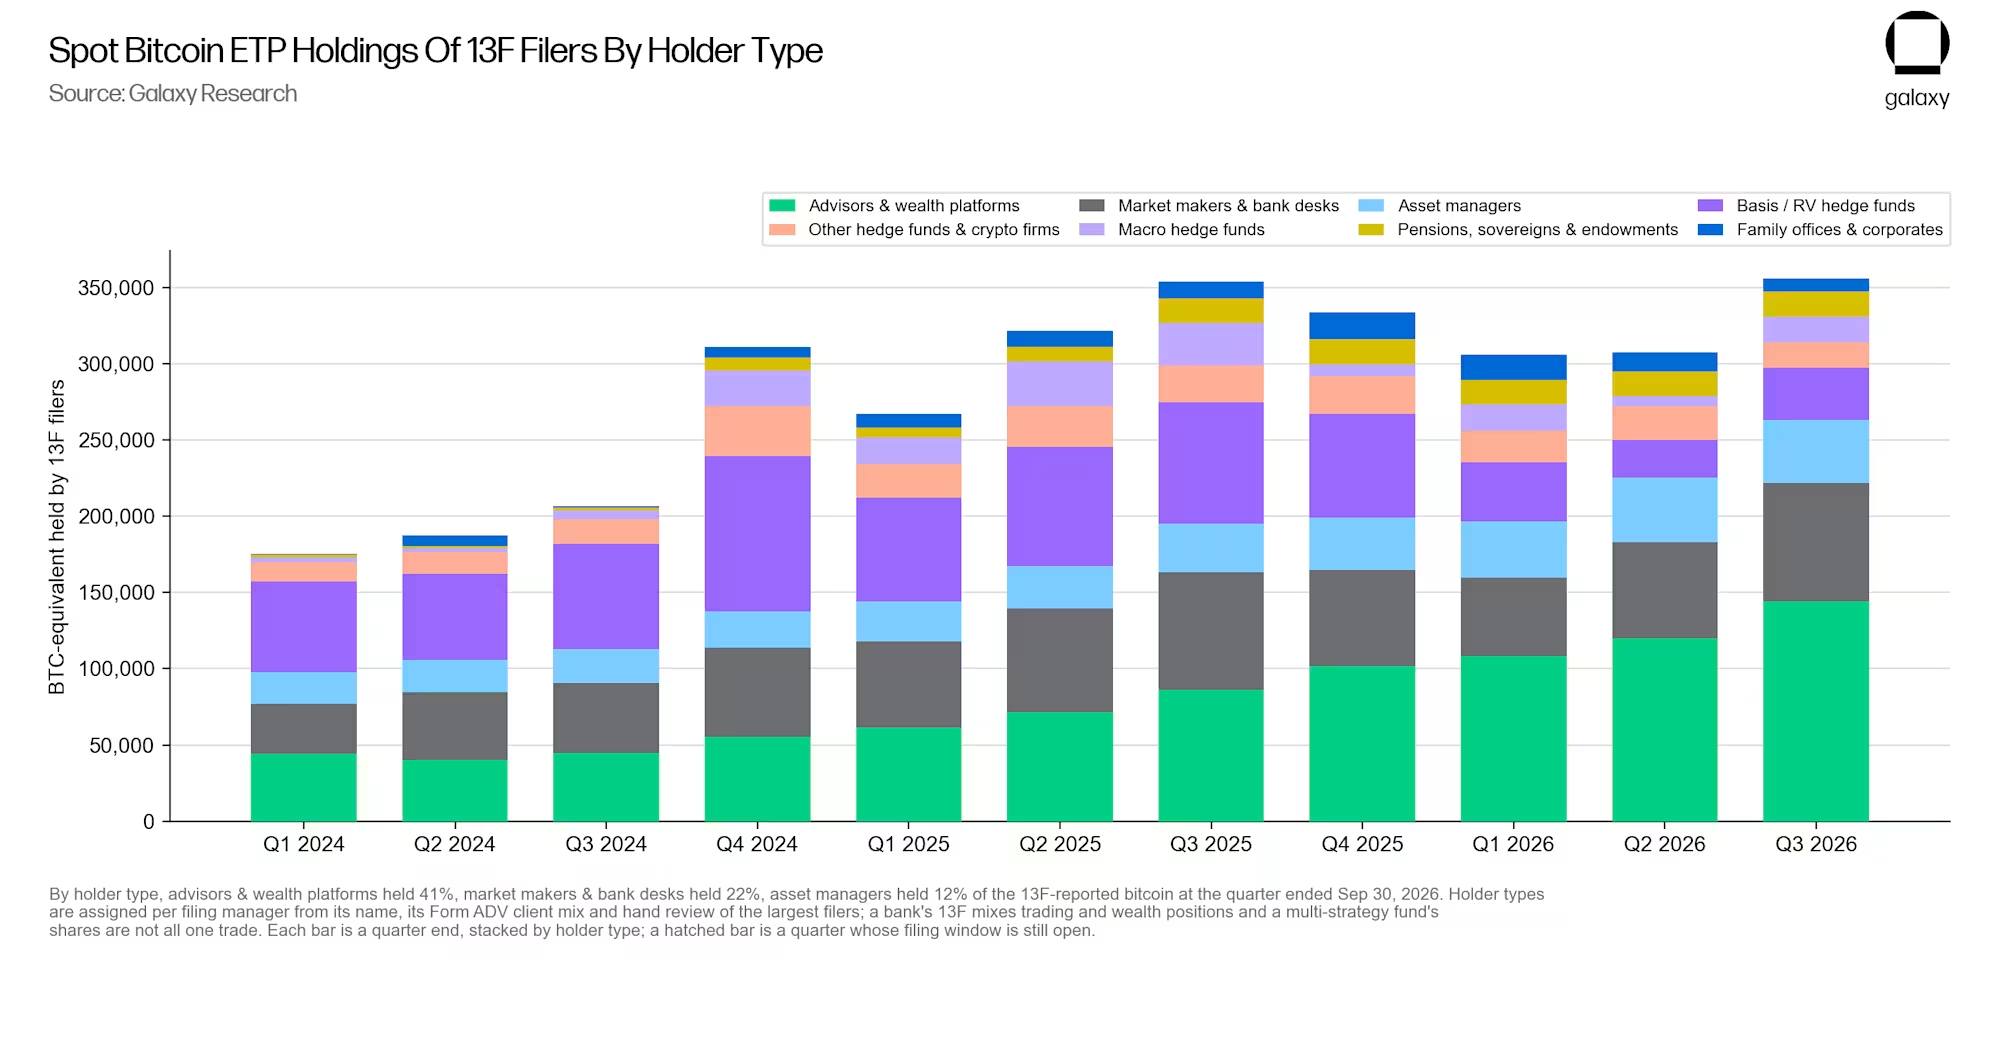
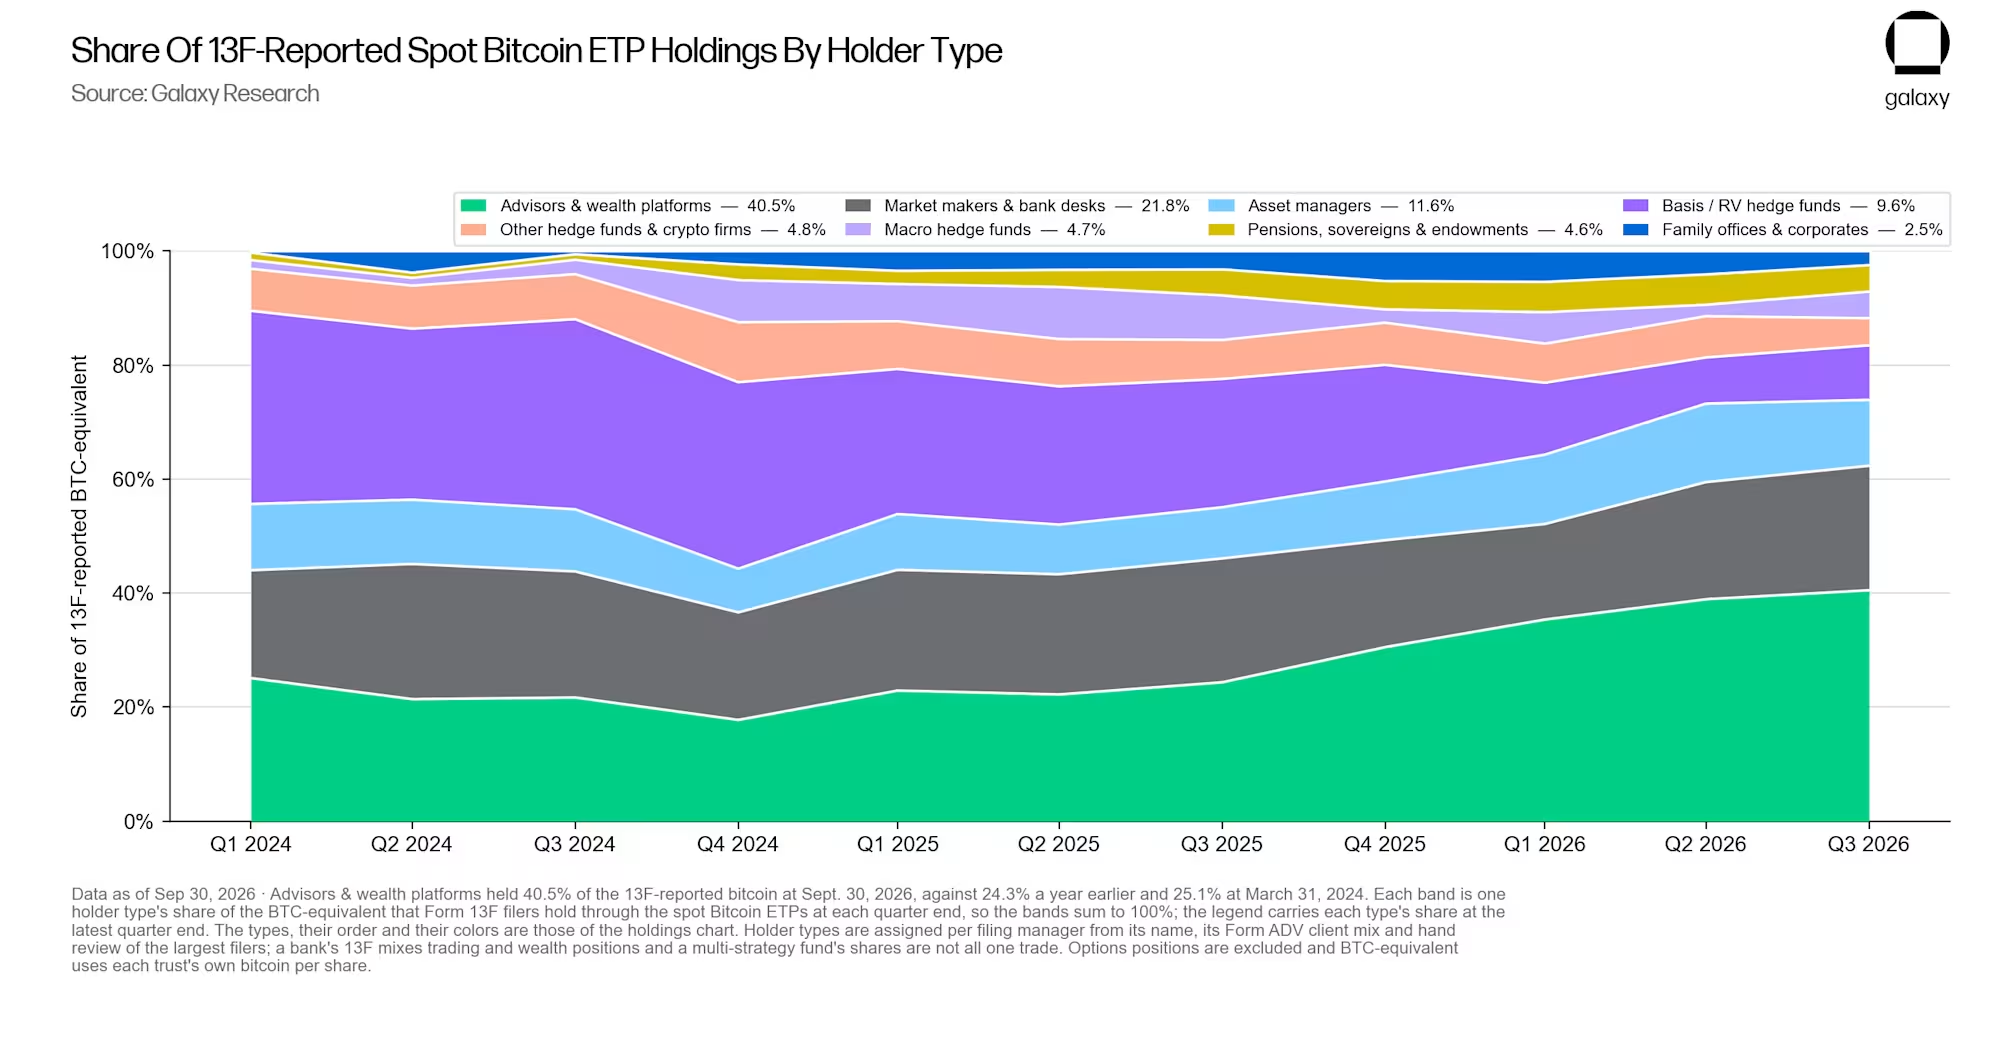
Investment advisers and wealth-management platforms were a notable source of growth. Their reported holdings reached 144,307 BTC equivalent, or 40.5% of the Bitcoin ETP holdings reported on 13F filings. That category includes both advisory firms and larger institutions with multiple business lines, so its total should not be read entirely as client portfolio allocations. The analysis notes, for example, that most of Bank of America’s reported position was in dealer and trading units.
What the filings cannot establish
The detailed breakdown puts 13F-reported holdings at 356,286 BTC equivalent, or 27.6% of the Bitcoin held by the spot ETPs at quarter-end. The source’s opening summary gives a slightly different reported-holdings figure of 356,491 BTC equivalent. Either way, the filings cover only a minority of ETP holdings.
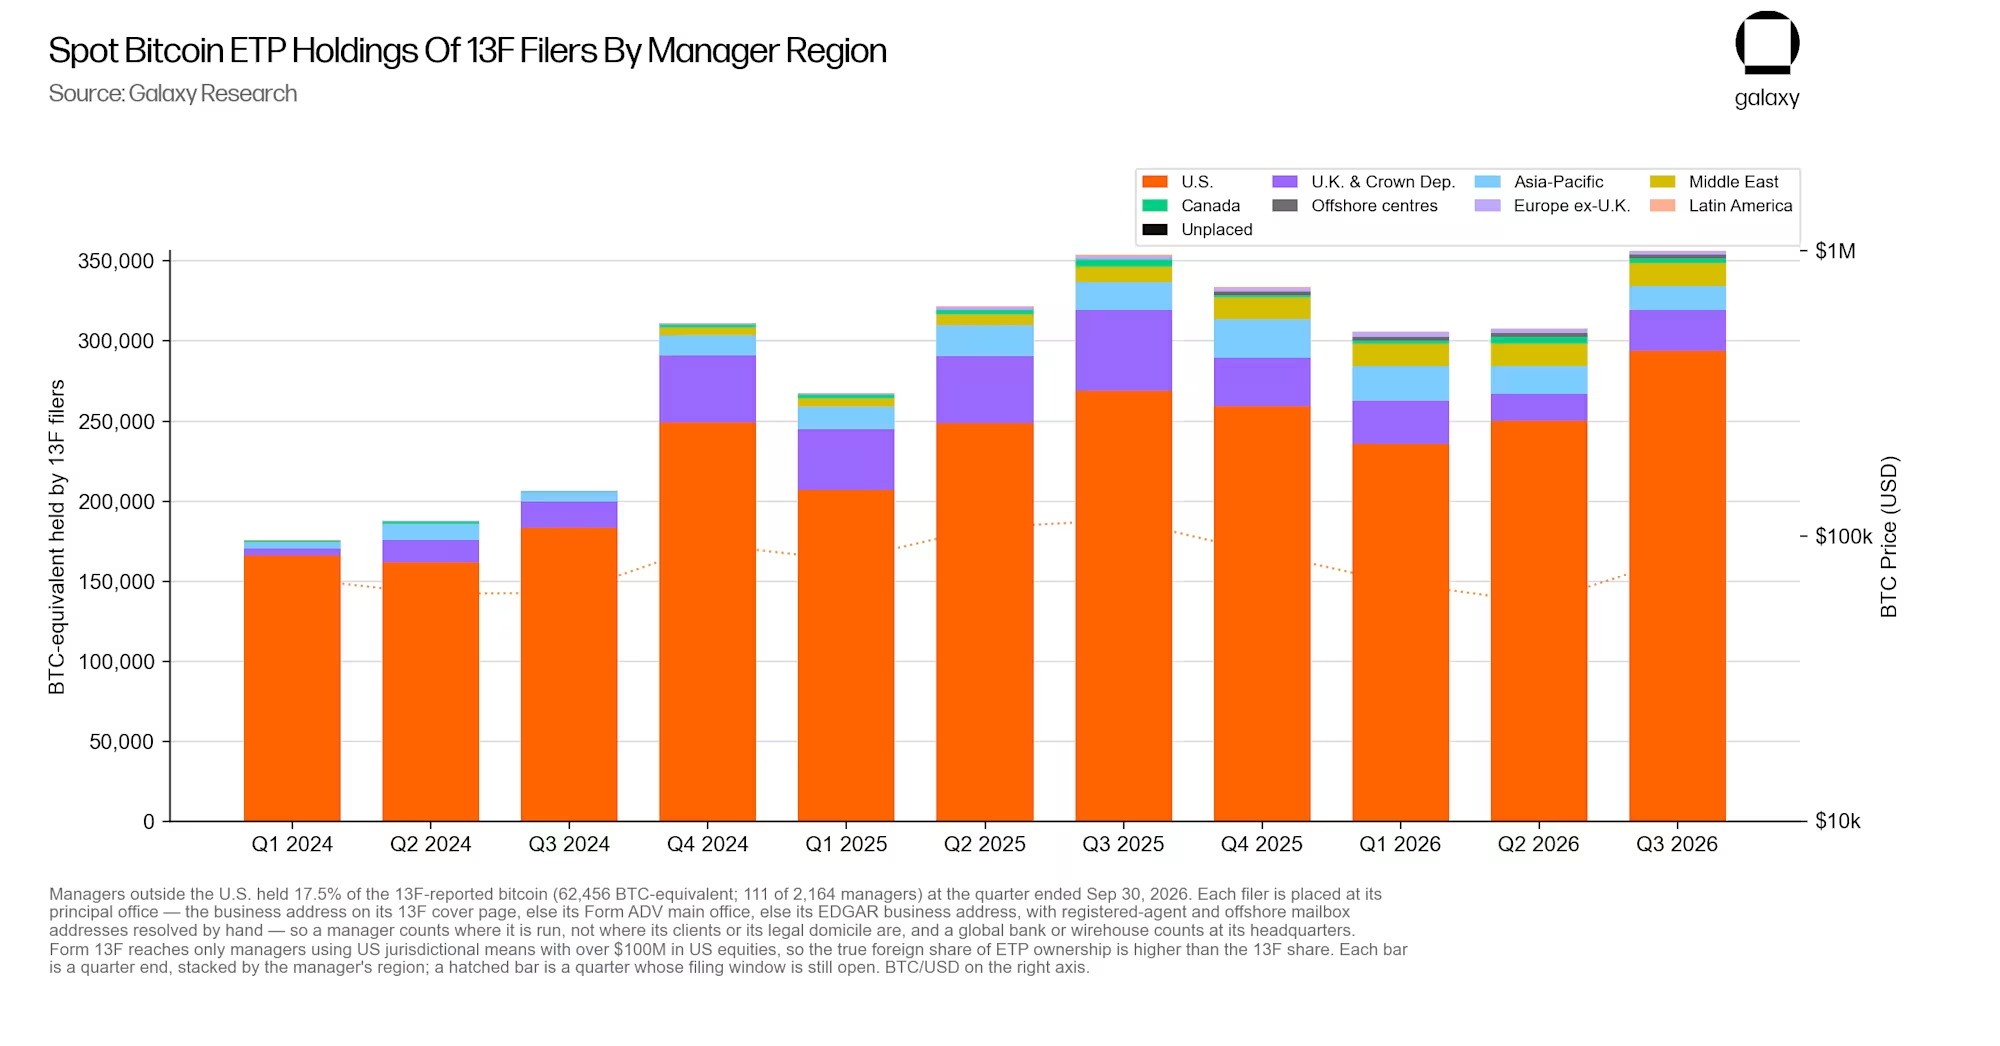
Form 13F reports quarter-end long positions in accounts over which a manager has investment discretion. It does not show short positions or most derivatives, so a market maker’s ETP shares may be hedged rather than a directional Bitcoin investment. Client-directed brokerage holdings are generally outside this view. The figures also reflect filings available by November 17, 2026; later or amended filings could change them.
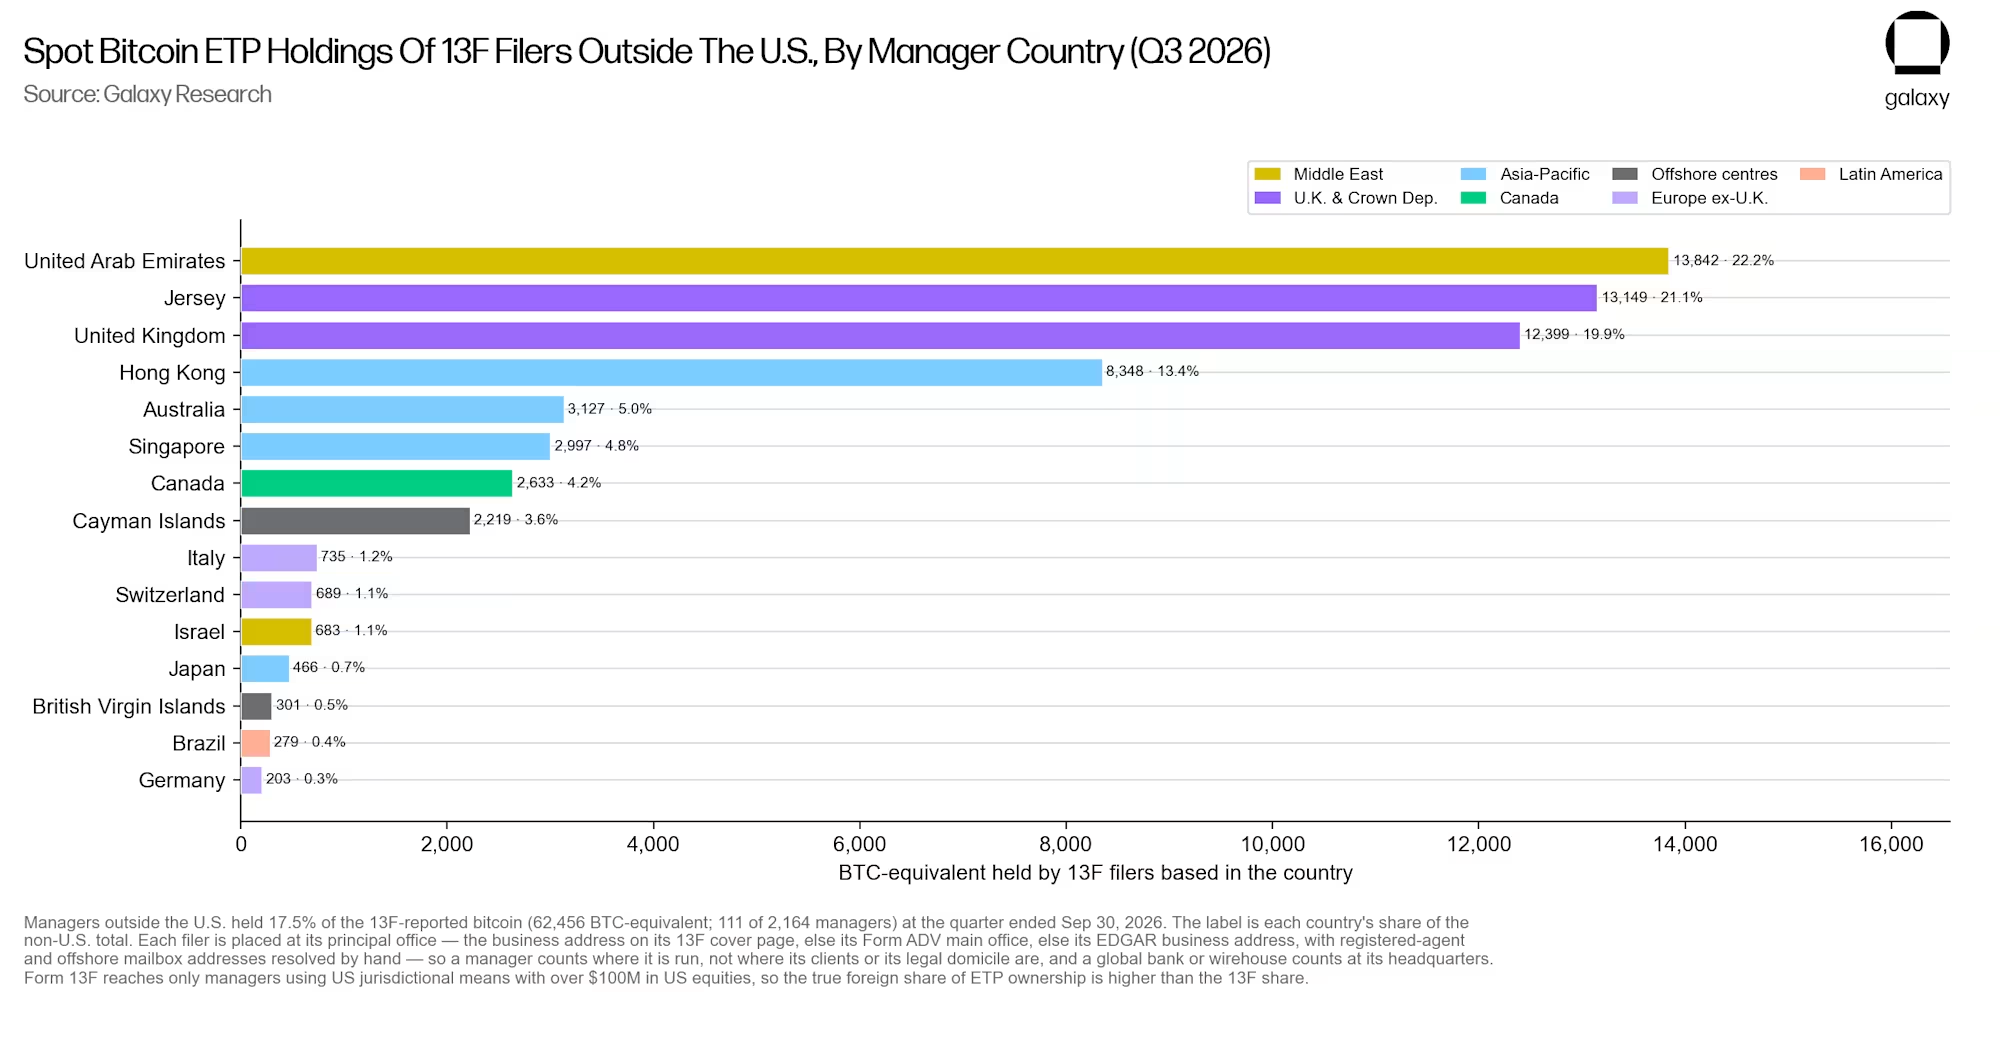
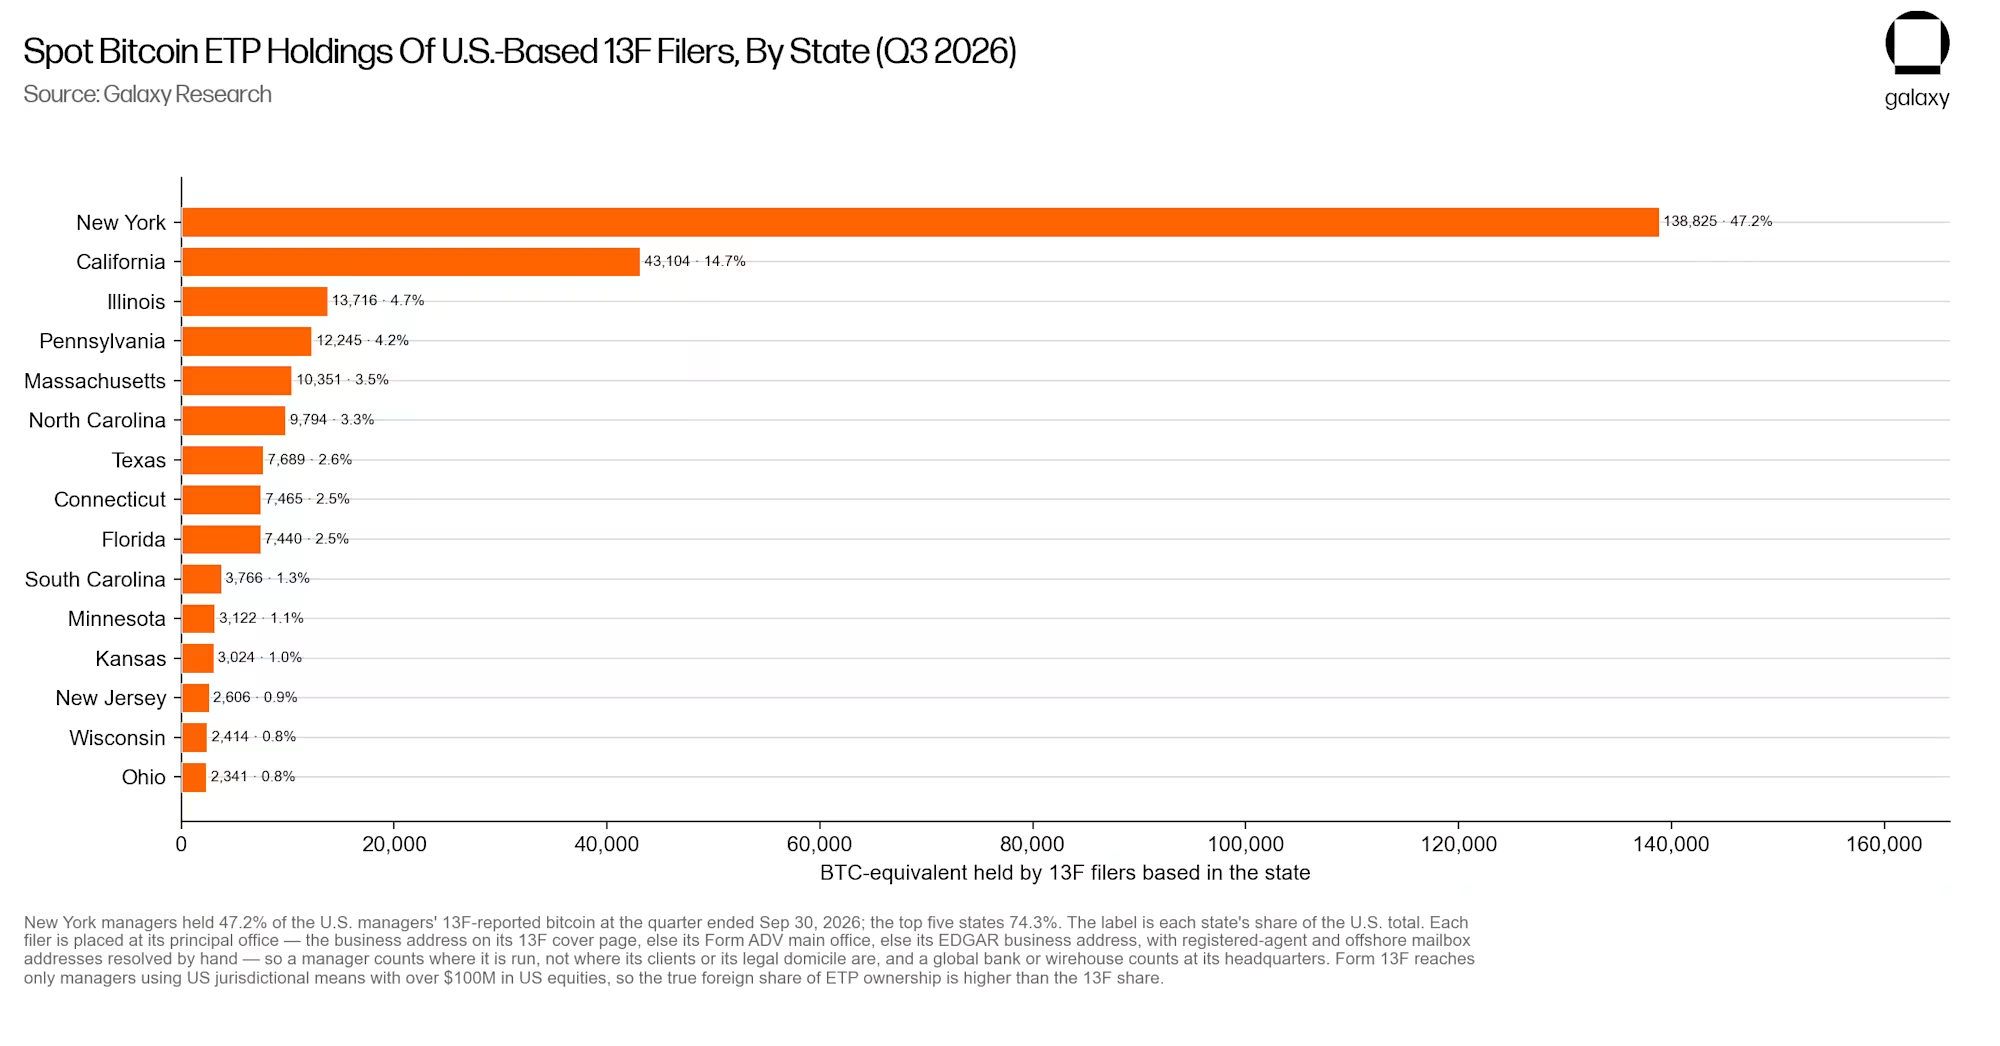
The quarter-end snapshot cannot explain subsequent trading. According to the analysis, the ETPs’ aggregate Bitcoin holdings fell by 38,531 BTC between September 30 and November 16, while Bitcoin’s price fell from $83,580 to $64,943. What the 13F-reporting managers did during that period was not yet visible in these filings. The durable takeaway is narrower than a claim of universal institutional buying: reported participation broadened, while the quarter’s net increase remained concentrated.